Business Funding · By Trifecta Business Group
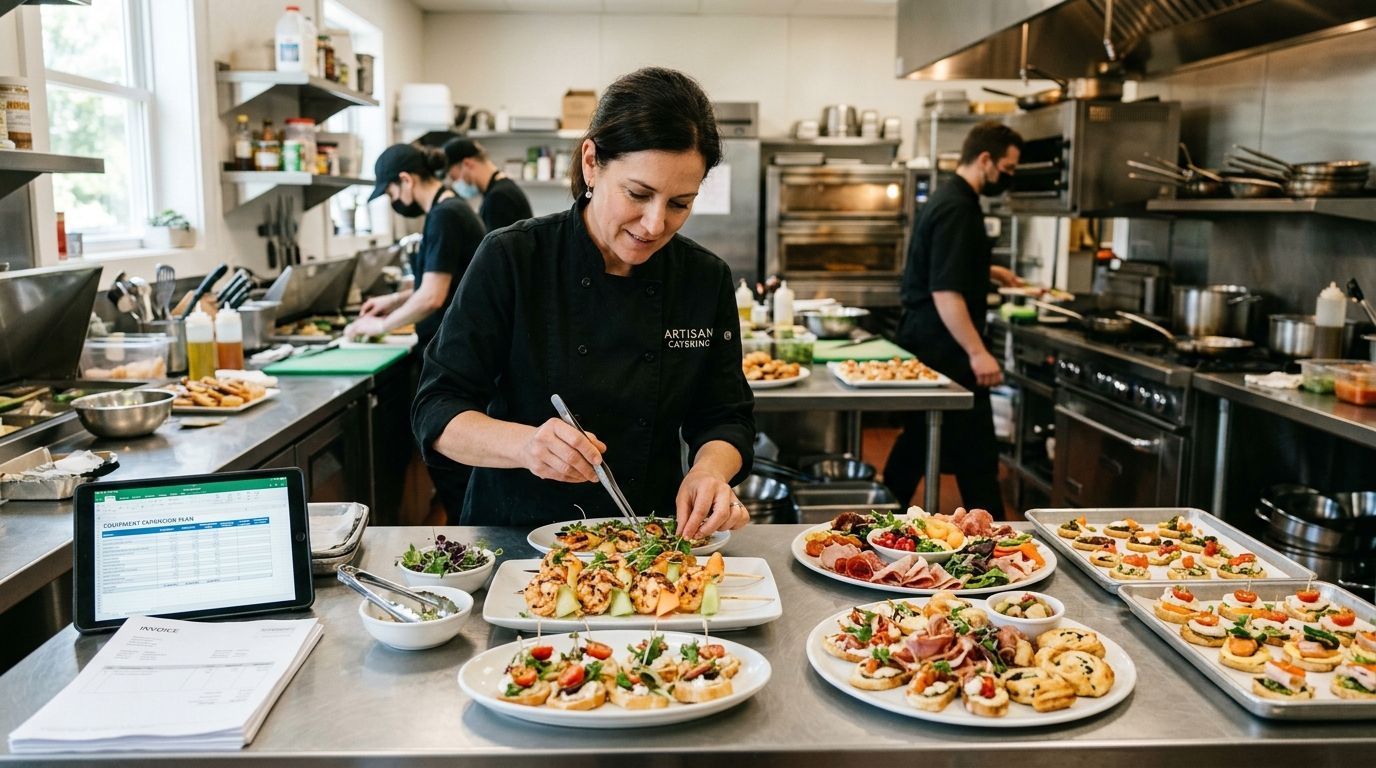
Business loans for catering companies fund equipment, staffing, and the cash gaps between events, and the right structure follows your booking calendar instead of a flat monthly schedule. Catering runs on wedding season surges, corporate event cycles, and holiday party crunches, so financing built for a steady-revenue business creates a repayment mismatch from day one.
- Working capital loans and lines of credit fit catering’s seasonal cash flow better than fixed term loans in 2026.
- SBA 7(a) loans cap at $5 million and work for kitchen buildouts or major equipment purchases.
- Invoice factoring turns net-30 and net-60 corporate event contracts into cash within 24-48 hours.
- Equipment financing lets you buy ovens, vans, and service gear without draining working capital before peak season.
- Applying during your strongest booking quarter gets approved faster than applying during a slow month.
Why business loans for catering companies matter
Catering revenue clusters around a handful of months, not a monthly subscription curve. Spring and summer carry wedding volume, fall brings corporate events, and November-December drive holiday parties, which means fixed costs like lease, staff, and vehicle payments continue through the slow stretch in between.
A working capital loan built for seasonal businesses bridges that gap without forcing a repayment structure designed for a business that earns the same amount every month. Catering companies also carry a specific asset risk: a broken commercial oven or a refrigerated van breakdown two weeks before a 300-person wedding isn't a maintenance issue, it's a lost contract and a damaged reputation with the venue and the client.
Funding decisions in catering come down to timing as much as amount. A loan that closes in six weeks doesn't help when a corporate client just signed a contract for an event in three.
Match your funding type to your booking calendar
Start by separating short-term cash gaps from long-term asset needs, because catering companies routinely finance both at once and mix them up.
- Use a working capital loan or line of credit for the gap between deposit and event date, or for slow months between seasons
- Use term financing for kitchen buildouts, second-location expansion, or a new fleet of service vehicles
- Use equipment financing for a single asset purchase like an oven, mixer, or delivery van
- Avoid stacking a merchant cash advance on top of existing debt just because approval is fast
- Match the repayment term to the life of the asset, not to how quickly you want the balance gone
Document your event pipeline before you apply
Underwriters lending to catering companies want to see forward bookings, not just trailing revenue, because a signed contract for a 400-guest gala in April tells them more about repayment ability than last month's bank statement.
- Pull signed contracts and deposit records for the next 6-12 months
- List repeat corporate clients and their typical annual spend
- Build a month-by-month revenue history covering at least 12-24 months
- Separate event-based revenue from ancillary income like retail or drop-off catering
- Have your catering license, health permit, and liability insurance certificate ready to attach
Finance equipment instead of paying cash for it
Commercial kitchen equipment and vehicles are long-lived assets, and paying cash for them ties up working capital you'll need the moment booking season slows. Equipment financing structures the payment against the useful life of the asset instead of your monthly cash position.
- Commercial ovens, combi steamers, and walk-in refrigeration
- Refrigerated delivery vans and service vehicles
- Chafing dishes, warming equipment, and event service gear
- POS systems, inventory software, and catering management platforms
- Keep working capital reserved for payroll and ingredient costs, not depreciating equipment
Turn unpaid invoices into cash
Corporate clients and large event venues routinely pay on net-30 or net-60 terms, which leaves catering companies fronting labor and ingredient costs weeks before payment arrives. Invoice factoring advances cash against those outstanding invoices instead of making you wait out the payment term.
- Corporate accounts with established net-30/60 payment terms
- Large event contracts where a deposit covers only part of the total
- Repeat institutional clients like hotels, hospitals, or conference centers
- Factoring works on invoice quality, not just your business credit score
- Best used selectively on your slowest-paying accounts, not your entire receivables book
Build a line of credit before you need it
Apply for a business line of credit during your strongest quarter, when your bank statements and booking pipeline both look strong, not in the middle of a slow month when you actually need the cash.
- Open the line while revenue is peaking, even if you don't draw on it yet
- Use it strictly for short-term gaps between deposit and event date
- Keep the balance near zero between draws to preserve availability
- Treat it as a cash flow buffer, not a source of growth capital
- Revisit the credit limit annually as your event volume grows
Prepare a catering-specific application package
Lenders reviewing a catering business ask for a few documents beyond the standard financial package, and having them ready shortens the timeline meaningfully.
- Two years of business tax returns and year-to-date financials
- Signed event contracts and a forward booking calendar
- Current health department permit and catering license
- General liability and commercial auto insurance certificates
- 3-6 months of business bank statements
Compare lenders on speed, not just cost
A cheaper loan that takes eight weeks to close doesn't help a catering company that needs a delivery van repaired before next weekend's bookings.
| Option | Best For | Funding Speed | Key Limitation |
|---|---|---|---|
| Working capital loan | Bridging slow months between events | Days to about 1 week | Repayment continues even if bookings slow further |
| SBA 7(a) loan | Kitchen buildouts or major equipment | Several weeks to months | Heavy documentation, slow close |
| Equipment financing | Ovens, vans, service equipment | Days to 2 weeks | Covers only the financed asset |
| Invoice factoring | Corporate clients on net-30/60 terms | 24-48 hours | Reduces margin on the factored invoice |
| Business line of credit | Ongoing seasonal cash gaps | 1-2 weeks to open | Requires discipline to avoid a standing balance |
A catering company juggling wedding-season deposits and corporate net-30 accounts usually needs two of these tools running at once, not one.
Common mistakes catering companies make
- Financing a commercial oven with a merchant cash advance because approval is fast, then paying it down out of next season's peak revenue before that revenue can fund growth
- Applying for a line of credit during the slow winter month when the need is obvious, instead of during peak booking season when the financials support approval
- Treating client deposits as spendable cash rather than a buffer against event cancellations or postponements
- Mixing equipment purchases and working capital into a single loan, which makes the repayment term wrong for at least one of the two uses
- Skipping health permit and insurance documentation on the application, which adds weeks to underwriting that a complete package would have avoided
Get Catering Business Funding Started
Talk through your booking calendar and funding options with a specialist.
FAQ
What’s the best business loan for a catering company in 2026?
A working capital loan or business line of credit fits most catering companies best in 2026 because it matches the seasonal booking calendar rather than a flat monthly schedule. Equipment financing or invoice factoring gets added on top depending on whether the need is a specific asset or slow-paying corporate invoices.
Can a new catering business get funding without two years of history?
Newer catering businesses can qualify for equipment financing or a smaller working capital loan using signed event contracts and a forward booking calendar in place of long financial history. Lenders weigh contract pipeline heavily for event-based businesses since it shows near-term revenue directly.
Is invoice factoring or a business line of credit better for a catering company?
Invoice factoring works best when the problem is slow-paying corporate clients on net-30 or net-60 terms, since it converts a specific invoice into cash within 24-48 hours. A business line of credit works better for general seasonal cash flow gaps that aren’t tied to a single unpaid invoice.
How much can a catering company borrow with an SBA loan?
SBA 7(a) loans cap at $5 million, which covers most kitchen buildouts, second-location expansion, or a full equipment fleet replacement for a catering business. SBA loans take longer to close than working capital or equipment financing, so they fit planned growth rather than urgent needs.
Do catering companies qualify for equipment financing on used equipment?
Equipment financing commonly covers used commercial ovens, refrigeration units, and vehicles, not just new purchases. The asset itself typically secures the loan, which is why approval focuses on the equipment’s condition and resale value as much as the business’s credit.
How fast can a catering business get working capital?
Working capital loans for catering companies typically fund within days once documentation is complete, compared to several weeks or months for an SBA loan. Speed depends heavily on having bank statements, event contracts, and permits ready before applying.
What documents does a catering company need for a loan application?
A catering company applying for funding needs two years of tax returns, recent bank statements, signed event contracts, a health department permit, and current liability and auto insurance certificates. Missing permit or insurance documentation is one of the most common reasons underwriting takes longer than expected.
One last thing
The catering companies that get approved fastest in 2026 apply during their strongest booking quarter, not the month they realize they're short on cash, because a lender reading a weak month in isolation sees risk where a full-year booking calendar would show a pattern.
Related guides
What are you trying to fund?
Compare flexible working-capital options
Start with working capital and a line of credit, then compare payment structure and speed.
Compare options