Trifecta Business GroupOur Passion, Your Growth
Equipment Financing & Leasing

Equipment Financing & Leasing

Quick answer: Equipment financing is commercial financing for new or used business equipment, such as machinery, vehicles and technology, often secured by the equipment itself. It fits businesses buying or leasing assets for business use. Approval, rates and amounts are not guaranteed. Timing depends on the program and the lender.

Reviewed by the Trifecta Business Group Editorial Team · Updated Nov 5, 2026

Explore commercial equipment financing and leasing for new or used business assets. One advisor matches your file to one lender at a time. No hard credit pull to explore your options. Approval, rates and amounts are not guaranteed. Timing depends on the program and the lender.

Accommodates unique credit stories Small and large equipment purchases Flexible leasing options

Matched to the right lender — one at a time, no hard credit pull to explore.

Trifecta Business Group, LLC BBB Business ReviewChamberofCommerce.com member badgeBBB profile &
Chamber member
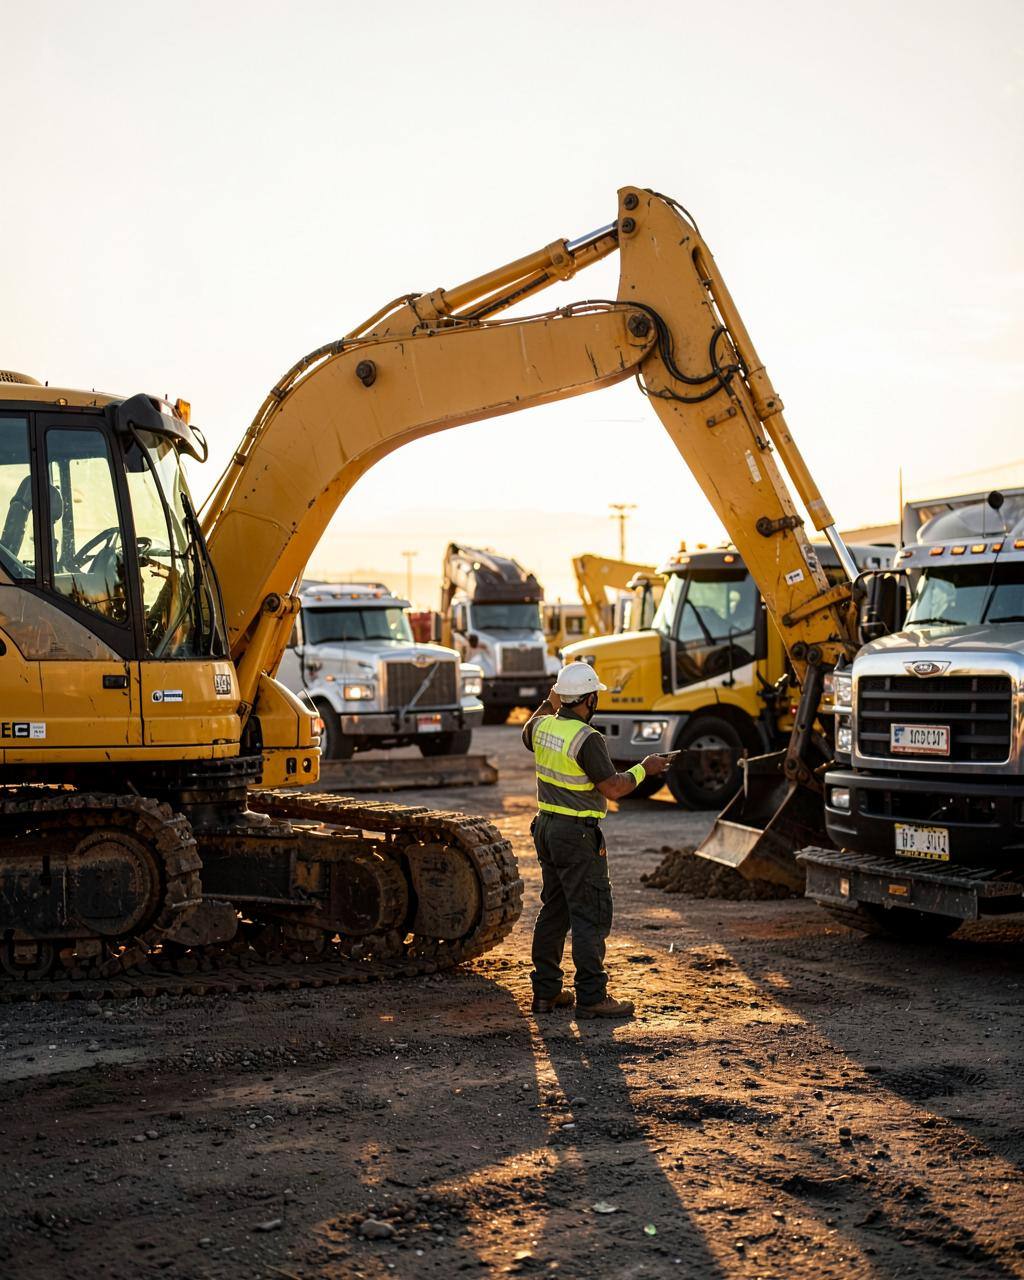
Commercial construction equipment and fleet trucks at a business yard at golden hour

Buying equipment for your business? You are in the right place — start below.

Sell or distribute equipment? Offer financing to your buyers through our Equipment Dealer Program →

Our borrower standard: one advisor, one matched lender, your file is never sold, and no hard credit pull to explore your options. Read our protection standards →

Have an equipment quote or invoice in hand?

Start with the price and the machine. Your advisor reviews the quote and matches it to one equipment lender, with no hard credit pull to explore options. Working against a dealer hold or auction date? Call so we know the deadline. Timing depends on the program and the lender.

Interactive Tool

Commercial Equipment Financing & Leasing Estimator

Instantly compare standard commercial loan payments against flexible capital lease structures. Adjust your equipment cost, rate, and term to see monthly payment estimates update in real time.

Deal Parameters

Enter your equipment cost, estimated rate, and preferred term to compare financing structures.

60 months (5 years)

Est. Standard Loan Payment
$2,052 /mo
Chattel Mortgage / Full Ownership
Est. $1 Buyout Lease Payment
$1,985 /mo
Capital Lease / $1 buyout (ask your tax advisor about tax treatment)
Check options for this amount — no hard pull

*Calculations are structural estimates. Real rates vary depending on credit profile and underwriting profiles.

One Matched LenderNo Credit Pull to ApplyAbout 3 minutes, plus upload

Our borrower standard

Borrower Protection Standards

Read the full standards →
01

One advisor, one matched lender

Your file goes to one lender at a time — never broadcast or auctioned.

02

Never sold to lead lists

Your information and documents are not sold to lead buyers.

03

No hard credit pull to explore

No hard credit pull to explore your options.

04

Commercial only, costs explained

Business-purpose financing; we walk through costs and payoff before you sign.

60-Second Eligibility Check

See which funding options you qualify for

Four quick questions. No hard credit pull, no documents, no phone call to get started — just a clear read on where your business stands against our lending partners. You can review the comparison tools immediately, then call or schedule time with our team for questions.

Step 1 of 5

How fast do you need the funds?

Speed is one of the biggest factors in which product fits — the fastest options cost more, the slower ones cost less.

One
One Matched Lender

One advisor, one lender at a time. Your file is never sold or auctioned.

$10K–$5M
Funding Range

From a small working-capital bridge to major expansion capital.

Your choice
No Obligation

Approval, rates and timing depend on underwriting and are never guaranteed.

About 3 minutes, plus upload
Application Time

Basic intake takes about 3 minutes, plus upload separately.

How It Works

Three steps from application to funded

Start step one
01

Apply — about 3 minutes, plus upload

Tell us your revenue, time in business and how much you need. About 3 minutes, plus upload. No hard credit pull to explore.

02

We match your file

A funding advisor matches your file to one suitable lender at a time, with your consent.

03

Review and get funded

Review any available terms with no obligation. Approval, rates and timing are never guaranteed.

Step 1 — about 3 minutes

Basic intake

  • Business name, address and industry
  • Ownership structure and owner details
  • Annual revenue and time in business
  • Contact info and how much you need
Step 2 — upload when ready

Full financing file

  • Recent business bank statements
  • Business tax returns
  • A debt schedule, if you carry existing loans
  • Any documents specific to your funding type
Speed it up

AI Autofill

  • Add short notes in any application section
  • Upload your documents and let AI map the fields
  • Cut your completion time down significantly
  • Reduce back-and-forth with your advisor later

Your documents stay private and secure. Bank statements, tax returns and debt schedules are transmitted over 256-bit TLS encryption and shared only with the lending partners matched to your request. We never sell your information.

High-Capacity Capital

Truck and Trailer Financing

Explore new or used trucks and trailers for business use. Asset details, cash flow, title and existing obligations guide the review; approval and amounts are not guaranteed.

Capital for Small and Large Purchases

From a single truck or machine to full fleet and facility upgrades.

Strategic Repayment Models
Fixed terms commonly 24 to 72 months via optimized capital leases or flexible operating lease formats.
Preserved Cash
Keep your liquid bank accounts intact for daily payroll, marketing, and operational agility.
The Conversation That Changes Everything

Construction Equipment Financing

Owners put off replacing equipment because they compare a monthly payment to zero. That comparison is wrong — and the fix starts with one honest question.

Your information is private and secure. Applications and documents are transmitted over 256-bit bank-grade TLS encryption, and your file is shared only with the lending partners matched to your request. We never sell your data, and the initial review involves no hard credit pull to explore your options.

Medical and Dental Equipment Financing

Explore imaging, diagnostic, treatment and other practice equipment for commercial use. Prepare vendor quotes, installation costs and business financials. Eligibility depends on the equipment, business and underwriting; approval is not guaranteed.

Restaurant Equipment Financing

Explore ovens, refrigeration, dishwashers, ventilation and other commercial kitchen assets. Include installation expenses and lease details. Compare proposed payments with operating cash flow. Approval and amounts are not guaranteed. Timing depends on the program and the lender.

Funded Case Snapshot

The Midwest · Towing & recovery

The situation. The heavy-duty wrecker — the only truck that could recover a box truck, bus, or loaded trailer — lost its transmission mid-recovery on a Sunday night. The rebuild quote came back at nearly half the cost of replacing a truck already past 400,000 miles. For six weeks the owner handed those calls to a competitor one town over, keeping the relationships alive by apologizing. His deposits still looked steady from the light-duty trucks, but the work he never got to bill was what actually hurt. He had been saving toward a second heavy unit anyway, about eighteen months short.

What we did.

  • Read the company's operating history, the deposit pattern across light and heavy work, and what the heavy calls had been worth before the truck quit.
  • Ruled out revenue-based financing — repayment moves with revenue, and his revenue would be lowest exactly while he rebuilt the call volume he had given away.
  • Ruled out a line of credit — a line is built for a gap that comes back every season, and he needed one truck, once, and planned to own it for the next decade.
  • Placed him on equipment financing, where the unit itself is the collateral — the money was structured against the wrecker instead of against the cash needed to keep four trucks rolling.

The outcome. He was back on heavy calls with the replacement shortly after applying. The county never had to go looking for anybody else.

Approval is never guaranteed, and timing depends on the program and the lender.

The financing

Equipment Financing

Amount placed:
About $75K
Timing:
Depends on the program and the lender
Apply Now
Also Available

Used Equipment Financing

If your machines, trucks, or production equipment are paid off or close to it, that equity is sitting idle. A sale-leaseback converts it into working capital while you keep using the equipment every day.

Your information is private and secure. Applications and documents are transmitted over 256-bit bank-grade TLS encryption, and your file is shared only with the lending partners matched to your request. We never sell your data, and the initial review involves no hard credit pull to explore your options.

How it works

A lender purchases the equipment from your business at an appraised value and leases it straight back to you. You receive a lump sum, keep possession and use of the asset, and make lease payments over the term. At the end you typically buy it back for a nominal amount.

What qualifies

Titled or serialized equipment with real resale value — heavy trucks and trailers, CNC and production machinery, construction and yellow iron, medical imaging, printing, and commercial kitchen build-outs. It should be owned free and clear or carry limited remaining debt that can be paid off in the transaction.

When owners use it

Covering payroll or tax obligations, funding a large job that requires cash up front, buying out a partner, consolidating higher-cost short-term debt, or bridging to a season when receivables land.

What to expect

Advances are based on appraised orderly-liquidation value, not what you originally paid. You'll need the equipment list with serial numbers, proof of ownership, and recent bank statements. Files with clean titles move fastest. Timing depends on the program and the lender.

Story-Driven Underwriting

Inclusive, Story-Driven Underwriting Standards

We believe a compressed net income on paper shouldn't hold your operational growth back. Underwriting looks at the big picture, not just one number.

01

Primary Document

A copy of the direct invoice or commercial quote for the specific equipment being purchased.

02

Flexible Credit Criteria

Welcomes both institutional investment-grade applicants and unique "story" situations (such as early-stage startups, turnarounds, or brands with positive EBITDA even if net margins are temporarily compressed).

More ways equipment can work for you

Beyond buying new from a dealer

Sale-leaseback: use equipment you already own

If your business owns machinery, trucks or titled vehicles outright, a sale-leaseback may turn that equity into working capital with fixed payments, instead of a daily-debit revenue advance. Eligibility, amount and terms depend on the equipment’s value and condition and are set by the funder after review.

Private-party and auction purchases

Buying from another business, a fleet sale or an auction? Many banks won’t finance a seller who isn’t a dealer. Share the listing or bill of sale and your advisor will check whether a lending partner will review it.

Commercial use only. Not an offer or approval; there is no hard credit pull to explore your options.

Replacing washers and dryers or buying a store? See laundromat financing.
Frequently Asked Questions

Questions, Answered

Used equipment may qualify depending on its condition, age, resale value and useful life. Bring a vendor quote, serial number or VIN and ownership details. Private-party or auction purchases may require additional review. Approval is not guaranteed. Timing depends on the program and the lender.

An equipment loan typically supports a purchase, while a lease has its own ownership and end-of-term provisions. Compare down payment, total payments, purchase options and return obligations. A capital lease or stated buyout is not automatically available. Ask your tax advisor about tax treatment.

Commercial trucks, trailers, construction machinery and medical or dental equipment may be reviewed for business use. Eligibility depends on the asset, vendor, business financials and existing obligations. One advisor matches your file to one lender at a time; approval and amounts are not guaranteed.

Start with an equipment quote or invoice, recent business bank statements and details about the intended use. Include serial numbers or VINs where applicable and disclose current financing obligations. Additional financial or ownership documents may be requested. Timing depends on the program and the lender.

There is no hard credit pull to explore your options. If you choose to move forward, a lending partner may request a credit review through its authorization process. Confirm inquiry requirements before consenting. Commercial financing only; approval, rates, amounts and timing are not guaranteed.

Run a payment first with the equipment financing calculator.

Apply Now

Apply for Equipment Financing via Trifecta Business Group

Send us your vendor quote and we'll structure a lease or finance package that keeps your cash reserves working where you need them most.

Timing depends on the program and the lender•No hard credit pull to start

Your information is private and secure. Applications and documents are transmitted over 256-bit bank-grade TLS encryption, and your file is shared only with the lending partners matched to your request. We never sell your data, and the initial review involves no hard credit pull to explore your options.

Start your file

Powered by Trifecta IQ

No hard credit pull to explore your options. Your data is encrypted in transit and never sold. Your details carry over so you don’t retype them.

By submitting, you agree that Trifecta Business Group may contact you by phone, email, or text message (including via automated technology) about your inquiry. Consent is not a condition of funding. Message and data rates may apply.

Prefer to talk it through? Call 1.877.977.3015

Interactive Tool

Equipment ROI & Break-Even Calculator

Equipment is not a cost sitting against zero — it produces revenue starting on day one while the payment stretches over years. Enter what the machine costs and what it earns to see whether it pays for itself.

The Machine & The Work It Does

Use the revenue the equipment brings in each month and your gross margin on that work.

$
%
yrs
$
%
How to use this number

Compare the monthly payment against the profit the equipment produces, not against zero. If net monthly cash is positive, the equipment is funding itself while you keep the capacity.

Net Monthly Gain
$2,202
Payment $1,848 vs. $4,050 monthly profit · pays for itself in about 21 months of production

Email me a copy of my results

We'll email your results and occasional funding updates. Unsubscribe anytime.

Estimate for planning purposes only. Excludes insurance, maintenance, fuel, and taxes. Actual rates and terms are set by the lender in underwriting.

What this calculator works out

This equipment ROI calculator compares the monthly payment against the revenue and margin the equipment produces, showing net monthly cash and how long the machine takes to pay for itself.

Do you qualify

Equipment Financing Qualification Snapshot

Equipment
New or used commercial equipment with resale value
Time in business
Established businesses and startups both reviewed
Down payment
Often 0–20%, depending on credit and asset type
Documents
Equipment quote or invoice plus recent bank statements

Typical starting points. Final terms vary by lending partner and are never guaranteed.

Equipment Loan vs. Equipment Lease

Equipment LoanEquipment Lease
OwnershipYou own the equipment from day oneLessor owns it; buyout options at term end
Upfront costMay require a down paymentOften lower upfront cost
Best forLong-life assets you plan to keepTech or assets you upgrade often
CollateralThe equipment itself secures the loanThe equipment itself secures the lease
Check your eligibility — no login

Common questions

Real questions owners ask about equipment financing

Can I finance equipment with a 600 credit score?

Often yes. The equipment itself is collateral, so many programs are more flexible on credit than unsecured loans. Expect a larger down payment or higher rate at lower scores.

Should I lease or buy business equipment?

Buying with a loan builds ownership. A lease can lower monthly payments and makes upgrading easier for equipment that ages quickly. Your accountant can advise on the tax treatment.

Run the Equipment ROI calculator →

Can I finance used equipment?

Many programs finance used equipment, sometimes with shorter terms based on the equipment's age and resale value.

How much down payment does equipment financing need?

Anywhere from 0% to around 20% is common, depending on credit, time in business, and the type of equipment.

Guides on equipment financing

Figures are general estimates, not offers or lender-confirmed terms.

Owners comparing this also look at

⚠ Important Financial Disclosures & Legal Compliance Notice

Informational & Analytical Purposes Only: All interactive calculators, estimation tools, text graphics, and software models provided on this landing page are intended exclusively for illustrative, informational, and preliminary analytical business budgeting purposes. Calculations, potential returns, interest factors, cash advances, and loan payment projections displayed by these tools are theoretical mathematical simulations based on user input parameters and do not represent verified financial advice, binding legal agreements, guaranteed contract conditions, or an official commitment or offer to extend commercial credit or financing.

Underwriting & Credit Approval Profiles: Actual funding approvals, transactional factor rates, loan-to-value (LTV) limits, advance distribution margins, loan durations, and legal terms fluctuate dynamically based on rigorous independent underwriting evaluation criteria. These evaluations include, but are not limited to, verifiable historical business cash flow structures, bank deposit frequencies, corporate merchant credit score, time in operation, asset evaluations, industry risk profiles, and macroeconomic market constraints. Not all applying business entities or applicants will satisfy standard criteria or qualify for peak premium advertised funding limits, rates, or programs.

Commercial Lending Limitation: The products, alternative capital options, and commercial services outlined on this website are explicitly designed for commercial, business, operational expansion, and investment purposes only. These services are completely prohibited from being utilized for personal, family, home residential consumer mortgage financing, or household consumption use.

© 2026 Trifecta Business Group, LLC. All rights reserved. Translate-IQ™, Capital Pulse™ and The Breakthrough Process™ are trademarks of Trifecta Business Group. Automated scraping or reproduction of site content and tools is prohibited. Alternative commercial funding structures and loan products may be issued, processed, or backed through our lending partners. Rates, structural terms, and operational program limits are subject to modifications or suspension at any time without advance written notification.

Our Passion, Your Growth

Bring us the goal. We’ll help clarify the route.

Trifecta Business Group