Business Funding · By Trifecta Business Group
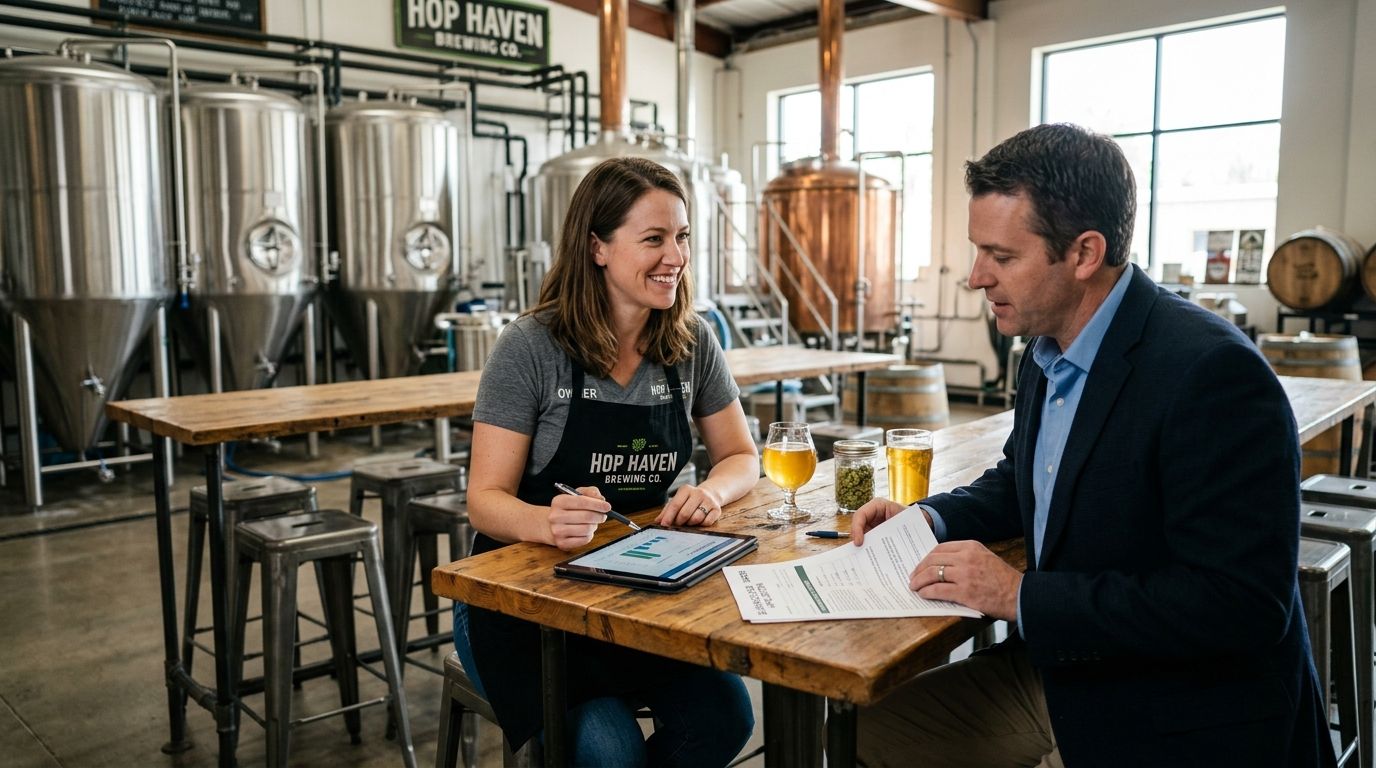
Business loans for craft breweries are financing tools sized to a business that spends heavily upfront (tanks, kegging lines, cold storage) and waits weeks or months to convert grain into revenue. A brewery's cash cycle looks nothing like a retail shop's: money goes out for malt, hops, and TTB-bonded storage long before a single keg sells, and that gap widens every time production scales up.
- Business loans for craft breweries work best when matched to the asset: equipment loans for tanks and canning lines, credit lines for seasonal swings.
- SBA loans offer the longest terms for brewhouse buildouts but typically take 60-90 days to close in 2026.
- Equipment financing covers fermenters and canning systems without draining the working capital a brewery needs for hops and malt.
- Working capital loans built for restaurants translate directly to taprooms carrying payroll and distributor payment lag.
- Trifecta Business Group matches brewery owners to funding by production stage, not a single default loan product.
Why business loans matter for craft breweries
A brewery's balance sheet is unlike most small businesses applying for funding in 2026: production equipment ages out on a 5-10 year cycle, TTB compliance and excise tax obligations sit on top of normal operating costs, and demand swings hard around seasonal releases. Choosing the right funding option for business growth starts with knowing which of those pressures you're actually solving for.
A brewery buying a second fermenter has a different problem than one that's short on cash between distributor payment cycles. Lenders underwrite those two situations differently, and brewery owners who apply for the wrong product waste weeks getting declined or approved for terms that don't fit the asset.
The core issue: breweries carry more fixed capital per dollar of revenue than most small businesses, which means the loan type matters as much as the loan amount.
Size the funding to the brewing stage
A brewery in year one financing a 7-barrel system needs something different than a five-year-old operation adding a canning line for grocery distribution. Match the ask to where the business actually sits.
- Startup breweries: equipment plus buildout financing, often paired with an SBA loan for real estate or leasehold improvements
- Growth-stage breweries: working capital to smooth taproom cash flow while distribution ramps
- Expansion-stage breweries: larger equipment financing packages for canning or bottling lines that unlock new sales channels
- Multi-location breweries: a line of credit to cover payroll and ingredient costs across sites without re-applying each time
Separate equipment costs from working capital needs
Brewers who bundle a fermenter purchase and six months of payroll into one loan often overpay on the equipment or underfund the cash flow gap. Split the ask.
- List every piece of equipment by cost and expected useful life — a 15-barrel tank outlasts a canning line component by years
- Estimate monthly cash flow separately, including excise tax payments and distributor payment terms
- Apply for equipment financing against the hard asset, not against projected sales
- Keep a working capital cushion outside the equipment loan for ingredient price swings
Build brewery-specific financials before you apply
Generic small-business statements miss the line items a lender evaluating a brewery cares about: TTB bond costs, excise tax accruals, and a cost of goods number that moves with hop and grain pricing.
- Break out cost of goods sold by batch, not by month, so seasonality shows clearly
- Track keg deposits and returns separately from taproom retail sales
- Document distributor payment terms (net 30, net 60) since they drive cash flow timing
- Include TTB compliance and excise tax as a fixed monthly obligation, not a variable one
- Show taproom revenue and wholesale revenue as separate lines
Match the loan term to the equipment's useful life
The most common structuring mistake in brewery financing: a 12-month repayment term on equipment that will run for 10 years. That mismatch strains monthly cash flow for no reason.
- Match term length to the equipment's expected working life, not to the fastest approval
- Avoid short-term products for anything bolted to the floor
- Confirm whether the lender allows early payoff without a penalty if sales outperform projections
- Build in a buffer for maintenance on used or refurbished brewing equipment
Strengthen the application with the right documentation
Breweries get declined more often for incomplete documentation than for weak financials. Lenders want the same numbers a brewer already tracks internally, organized the way underwriting reads them.
- TTB permit and bond documentation
- 12-24 months of bank statements showing taproom and wholesale revenue separately
- A batch-level cost of goods breakdown
- Equipment quotes or invoices for anything being financed
- Distribution agreements or letters of intent, if applicable
- A cash flow projection that accounts for excise tax timing
Avoid overleveraging distribution before capacity supports it
Breweries that finance a distribution push before production capacity can support it end up carrying debt payments against sales they can't fulfill. Confirm the capacity math before signing.
- Calculate maximum monthly production output against projected distribution volume
- Confirm cold storage and packaging capacity can handle new distributor orders
- Stage financing in phases tied to confirmed distribution agreements, not projected ones
- Keep a reserve for the lag between shipping product and getting paid
Compare funding built for capital-intensive production
The options below cover the funding types breweries use most in 2026. None of them is a universal fit — pick based on what you're financing, not what's fastest to apply for.
| Option | Best for | Funding speed | Key limitation |
|---|---|---|---|
| SBA loans for small business owners | Brewhouse buildouts, real estate, long-term expansion | 60-90 days | Heavy documentation, personal guarantee required |
| Equipment financing | Fermenters, canning lines, kegging systems | 1-2 weeks | Amount tied to the equipment's resale value |
| Business line of credit | Seasonal ingredient buys, payroll gaps | Days | Lower limits than a term loan |
| Working capital loans | Taproom cash flow, distributor payment lag | Days to a week | Shorter terms mean more frequent payments |
Verdict: an SBA loan is the right call for a brewhouse buildout or real estate purchase — buy the longer approval timeline when the term and rate justify it. Equipment financing is the correct tool for a canning line or fermenter — buy when the asset has a long, clear useful life. A line of credit or working capital loan is the fix for seasonal cash gaps, not equipment — skip either for a tank purchase, since the repayment schedule won't match the asset's life.
“If a brewhouse expansion pays for itself within the equipment’s useful life, it’s worth financing. If it only pencils out on optimistic sales projections, it isn’t.”
Common mistakes craft breweries make
- Financing a canning line with a short-term product. A six-month advance on a machine that runs for a decade strains monthly cash flow immediately.
- Leaving excise tax and TTB bond costs out of cash flow projections. Lenders catch this fast, and it undermines the rest of the application.
- Underestimating taproom buildout costs relative to the loan amount. Bar equipment, cold storage HVAC, and ADA compliance work add up well beyond the brewhouse itself.
- Mixing taproom retail and wholesale financials into one line. Underwriters can't evaluate margin or risk without the split.
- Chasing distribution deals before production capacity supports them. Signed agreements don't help if the brewhouse can't fill the orders on time.
Ready to fund your brewery’s growth?
Talk through equipment financing, SBA loans, or working capital built for breweries.
FAQ
What’s the best business loan for a craft brewery in 2026?
Equipment financing fits fermenters and canning lines best, while an SBA loan fits brewhouse buildouts and real estate. Working capital loans and lines of credit cover seasonal cash flow gaps, not equipment purchases.
Can a new brewery get SBA financing?
Yes, but a startup brewery needs strong personal credit, a detailed business plan, and often collateral because the business has limited operating history. Breweries with two or more years of financials have an easier approval path.
How does equipment financing work for a brewing operation?
The equipment itself serves as collateral, which usually means faster approval than an unsecured loan. Terms are generally structured to match the equipment’s useful life.
When should a brewery use a line of credit instead of a term loan?
A line of credit fits recurring short-term needs like ingredient purchases before a seasonal release or payroll during a distributor payment lag. A term loan fits a one-time purchase like a fermenter or canning line.
Is invoice factoring useful for craft breweries?
It helps breweries with wholesale accounts on net-30 or net-60 terms, since factoring advances cash against those invoices. It’s less useful for taproom-focused breweries with minimal B2B receivables.
How much collateral do craft breweries need for a loan?
It depends on the loan type. Equipment financing is usually collateralized by the equipment itself, while an SBA loan may require a personal guarantee and additional collateral depending on loan size.
Can a brewery use a working capital loan for seasonal swings?
Yes. Working capital loans are built for covering payroll and ingredient costs ahead of a seasonal release, before revenue catches up to expenses.
What documents does a brewery need for a funding application?
TTB permit and bond documentation, 12-24 months of bank statements with taproom and wholesale revenue split out, equipment quotes, and a cash flow projection accounting for excise tax timing.
One last thing
The brewery owners who get funded fastest in 2026 aren't the ones with the biggest revenue numbers. They're the ones who show up with taproom and wholesale revenue already split apart, excise tax already accounted for, and a specific answer to what the loan finances. Underwriting moves quickly when the numbers arrive organized the way it needs to read them.
Related guides
- How to prepare your business for a funding application
- Best working capital loans for seasonal businesses
- How to improve cash flow with working capital financing
What are you trying to fund?
Compare flexible working-capital options
Start with working capital and a line of credit, then compare payment structure and speed.
Compare options