Business Funding · By Trifecta Business Group
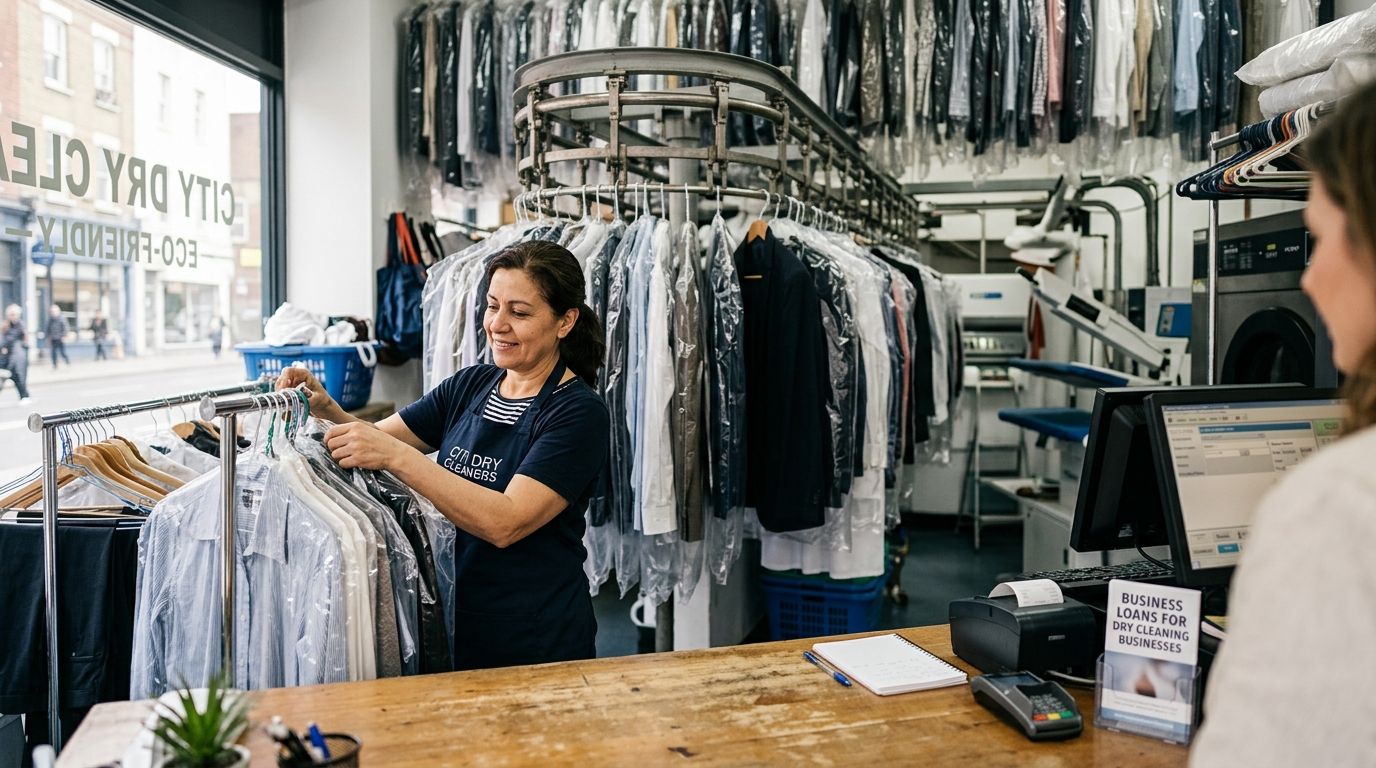
Business loans for dry cleaning businesses fund equipment replacement, lease buildouts, and the seasonal cash gaps that come with a service running on machines older than the owner's mortgage. Dry cleaners carry a different risk profile than most retail storefronts: heavy upfront equipment cost, thin margins on pressing and alterations, and revenue that dips every summer when customers stop wearing suits. Lenders price around those specifics, which is why a generic small business loan pitch usually misses the mark for this segment.
- Dry cleaning funding in 2026 splits three ways: equipment financing, working capital lines, and SBA-backed term loans.
- Machinery drives most requests — a single dry-to-dry unit or boiler often costs more than a year of rent.
- SBA 7(a) goes up to $5 million, with terms up to 10 years for equipment and 25 years for real estate.
- Merchant cash advances fund in 24-72 hours but cost the most. Emergencies only.
- Trifecta Business Group structures funding around a dry cleaner’s actual seasonal cash cycle, not a template.
Why funding matters for dry cleaning businesses
A dry cleaning plant lives and dies by its machines. A dry-to-dry cleaning unit, a steam boiler, or a pressing line is a capital expense most independent owners cannot cash-flow out of pocket, and financing that equipment on the wrong terms locks up working capital for years. Add the seasonality every dry cleaner sees — heavier suit and coat volume in spring and fall, lighter volume mid-summer — and cash gets tight at predictable, recurring points in the calendar.
Dry cleaners in 2026 also compete against wash-and-fold and on-demand pickup services that barely existed a decade ago. That pushes owners toward funding for delivery vans, route software, and marketing, not just machinery. It is a different funding shape than a restaurant or a clothing store faces, and the right funding option for business growth depends on which of those needs is actually driving the request.
The quotable verdict: for equipment and plant purchases, an SBA 7(a) term loan wins for dry cleaners who can wait 30-60 days; for the recurring summer dip, a business line of credit is the better instrument.
How to fund a dry cleaning business in 2026
Price the equipment before you price the loan
Most dry cleaning capital requests start with a machine. Get the machine numbers straight before a lender ever sees an application.
- Get written vendor quotes on the specific unit — dry-to-dry, press, boiler — not a category estimate
- Note the expected useful life; commercial dry cleaning machinery commonly runs 10-15 years with maintenance
- Decide between financing (you own it at term end) and leasing (lower monthly payment, no ownership)
- Ask whether the equipment vendor finances directly, since vendor terms sometimes beat a bank
- Include installation and utility hookup costs, which are routinely left out of first-draft budgets
Map your seasonal cash flow gap
Dry cleaning revenue swings by season more than most retail categories. Measure the swing before borrowing against it.
- Pull 12 months of revenue and mark the two or three weakest months
- Total fixed costs for those months: rent, payroll, utilities, solvent and supply contracts
- Subtract from cash reserves to get the real gap number
- Classify it: recurring pattern (needs a standing line) or one-time event (needs a term loan)
- Borrow the gap, not a round number that feels comfortable
This is where working with a firm that reads the cash cycle helps. Trifecta Business Group sizes funding against the actual low months rather than an annual average, which keeps dry cleaners from carrying debt service through the months they least need it. The same logic applies across working capital loans for seasonal businesses.
Settle the lease or real estate question
Location drives dry cleaning volume more than almost any other variable. Parking access and drive-by traffic decide whether a plant fills its racks.
- Compare relocation cost against renewal cost on the current lease
- Price the equipment move separately — relocating heavy machinery is its own line item
- Ask the landlord for a build-out allowance before assuming you cover the full cost
- Model whether a longer lease term buys a lower rate
- Check whether an SBA 504 or 7(a) structure fits if you are buying rather than leasing
Apply for SBA-backed term financing
SBA loans remain the lowest-cost route most dry cleaners qualify for. The tradeoff is time and paperwork.
- SBA 7(a) reaches $5 million, with terms up to 10 years for equipment and 25 years for real estate
- Prepare two to three years of business tax returns plus personal financial statements
- Write a plan that shows machine replacement schedule and seasonal revenue pattern
- Budget 30-60 days from application to funding in 2026 — this is not a same-week product
- Start the file before the machine fails, not after
Set up short-term funding for genuine emergencies
When a boiler dies on a Tuesday and there is no time for a 60-day approval, faster money exists. It costs more.
- A merchant cash advance can fund in 24-72 hours against future card receipts
- A business line of credit gives repeat access without a new application each time
- Match the repayment window to the length of the actual problem
- Compare total repayment cost, not the monthly payment, across every option
- Keep the advance for the repair itself, not for general operating drift
Build business credit ahead of the need
Owners who check their credit profile during a crisis get crisis terms. Build the file in the quiet months.
- Pull the business credit report and dispute errors now
- Keep business card utilization under 30%
- Pay solvent, hanger, and bag suppliers on terms that report to bureaus
- Separate personal and business accounts completely
- Review how to build business credit for better loan terms before your next application cycle
Comparison: funding options for dry cleaning businesses
| Option | Best for | Typical speed | Key limitation |
|---|---|---|---|
| SBA 7(a) term loan | Equipment purchase, plant buildout, real estate | 30-60 days | Heaviest documentation, longest wait |
| Equipment financing | Replacing a dry-to-dry unit, press, or boiler | 5-10 days | Secured by the machine; limited to that asset |
| Business line of credit | The recurring summer revenue dip | 3-7 days | Ongoing qualification review; variable rate |
| Merchant cash advance | Emergency repair with no time to wait | 24-72 hours | Highest effective cost of any option here |
Buy: SBA 7(a) for any machine you intend to keep a decade. Hold: a line of credit opened before you need it, drawn only in the weak months. Skip: a merchant cash advance for anything you could have planned three months earlier.
“Match the loan term to the machine’s real lifespan first, then shop rate. A 12-year machine on a 3-year note doubles the payment for nothing.”
Get funding built around your plant
Equipment, seasonal cash flow, or SBA options — mapped to your numbers.
Common mistakes dry cleaning owners make
- Financing a 12-year machine on a 3-year term. The monthly payment doubles and the working capital disappears for no operational gain.
- Starting the application after the breakdown. A 30-60 day SBA timeline is useless when the boiler is already cold, which pushes owners into the most expensive product on the table.
- Borrowing a flat annual number instead of the seasonal gap. Dry cleaning revenue is not flat, so flat debt service is a mismatch by design.
- Running payroll and supplier payments through a personal account. It slows underwriting in 2026 and produces worse pricing on every product.
- Treating a merchant cash advance as ongoing working capital. It is built for a two-week problem, and the cost compounds fast past that window.
FAQ
What’s the best business loan for a dry cleaning business in 2026?
For equipment, plant buildout, or real estate, an SBA 7(a) term loan is the best option because it carries the longest terms available — up to 10 years for equipment and 25 years for real estate. For the recurring seasonal dip, a business line of credit fits better since it does not require a new application each time.
How fast can a dry cleaner get funded?
Equipment financing commonly funds in 5-10 days and a merchant cash advance in 24-72 hours. SBA loans take 30-60 days from application to funding, so speed and cost trade directly against each other.
Is a merchant cash advance better than a business loan for a dry cleaner?
No, not for anything you can plan. A merchant cash advance carries the highest effective cost of the options on this page and works only when a repair cannot wait for underwriting.
Can a new dry cleaning business qualify for a loan?
Yes, though newer businesses lean harder on personal credit and a written plan because they lack two to three years of tax returns. Equipment financing is often the most accessible first product since the machine itself secures the debt.
Should I lease or finance dry cleaning equipment?
Finance it if you plan to run the machine through its full 10-15 year life and want ownership at the end. Lease it if you need the lower monthly payment and expect to swap the unit before then.
How much can I borrow with an SBA 7(a) loan?
SBA 7(a) loans go up to $5 million. Most independent dry cleaning plants borrow far less, sized to one or two machines plus buildout.
How do I cover cash flow during slow summer months?
Open a business line of credit before the dip and draw against it in the weak months. Map the last 12 months of revenue first so you know exactly how many months need coverage and how much.
What documents do lenders want from a dry cleaner?
Two to three years of business tax returns, personal financial statements, and recent bank statements are standard for SBA and bank term loans. Equipment financing usually requires less, since the asset carries the risk.
One last thing
The costliest funding mistake in dry cleaning is not lender choice — it is term length. Owners shop rate obsessively and accept whatever term the lender offers first, then spend a decade servicing a note that never matched the asset. Set the term against the machine's useful life, then negotiate rate. In 2026 that single reordering saves more money than any rate shopping exercise will.
Related guides
- Business loans for laundromats
- How to get equipment financing for your business
- Business line of credit for small business owners
What are you trying to fund?
Compare flexible working-capital options
Start with working capital and a line of credit, then compare payment structure and speed.
Compare options