Business Funding · By Trifecta Business Group
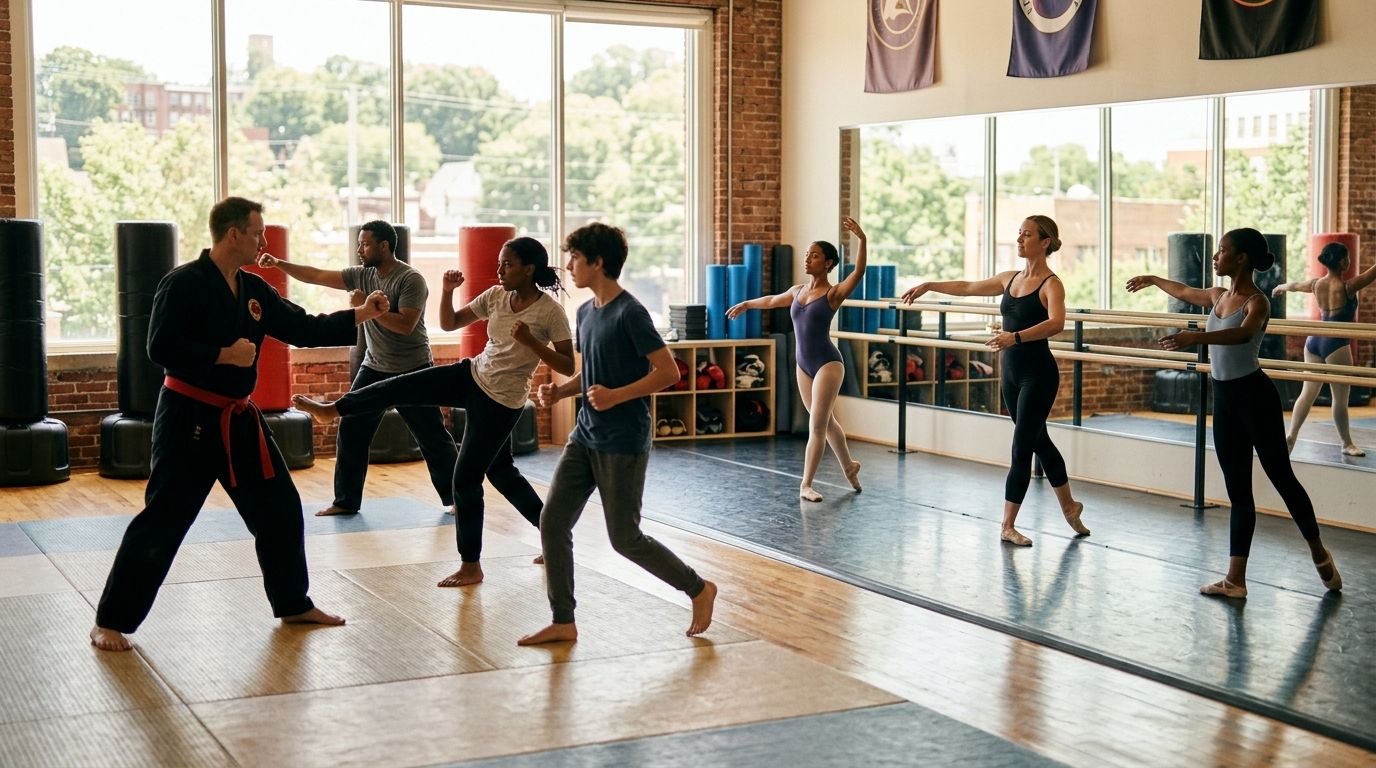
Business loans for martial arts and dance studios cover the gap between what a studio spends on space, staff, and equipment and what monthly tuition actually brings in — especially during summer enrollment dips or a lease renewal that forces a build-out. Studios run on recurring revenue but face lumpy costs: mat replacement, mirror walls, sound systems, and instructor payroll that doesn't pause just because enrollment dropped 20% in July. That combination of steady overhead and uneven cash flow is what makes funding for this segment different from a typical retail loan.
- Business loans for martial arts studios range from SBA term loans to short-term working capital, each suited to a different cash need.
- Seasonal enrollment swings mean a business line of credit often beats a lump-sum term loan for day-to-day cash flow.
- Equipment financing covers mats, mirrors, and sound systems without draining working capital reserves.
- Dance studios and martial arts schools qualify faster when time-in-business and monthly revenue are documented clearly.
- Trifecta Business Group matches studio owners to the funding structure that fits their enrollment cycle, not a generic template.
Why funding matters for martial arts and dance studios
A martial arts school or dance studio carries fixed costs — rent, instructor pay, insurance — against revenue that moves with the school calendar, weather, and local competition openings. Summer months routinely see enrollment drop as kids switch to camps and sports; January often brings a resolution-driven spike. That rhythm means a studio can be profitable on paper across 12 months and still short on cash in any given 30-day window.
Studios also carry equipment costs that don't show up in a typical service business: sprung floors, wall mats, mirrors, sound systems, and uniforms or costumes for recitals and belt tests. None of that is optional, and most of it needs replacing or expanding as class sizes grow. The right funding for martial arts and dance studios matches the loan structure to the actual timing of the expense — a mat replacement is a one-time capital cost, a slow August is a cash flow problem, and those two situations call for different products.
Steps to fund a martial arts or dance studio the right way
Map your cash flow against the school-year calendar
Before applying for anything, chart 12 months of revenue and expenses side by side. Studios that skip this step end up borrowing the wrong amount or the wrong term.
- Pull 12 months of bank statements or POS reports and mark enrollment peaks and troughs
- Flag the months where tuition revenue drops below fixed monthly overhead
- Note recurring one-time costs: recitals, tournaments, belt testing supplies
- Separate recurring subscription revenue (auto-pay tuition) from one-off event income
- Calculate your minimum cash runway during the slowest month of the year
Fix your bookkeeping before you apply
Lenders read financial statements as a proxy for how the business is run. Clean books move an application through underwriting faster and often improve the terms offered.
- Separate personal and business bank accounts if they're still mixed
- Reconcile merchant processor deposits (tuition auto-pay platforms) against your general ledger monthly
- Categorize equipment purchases as capital expenses, not overhead
- Keep 3-6 months of statements ready in PDF form, not screenshots
- Track member count and average tuition per student as a standing metric
Decide what the money is actually for
A loan for a new mat system and a loan for October payroll are not the same request, even if the dollar amount matches. Get specific before you talk to any lender.
- Equipment or build-out (mats, mirrors, flooring, sound): points toward equipment financing or a term loan
- Seasonal payroll gap: points toward a business line of credit or short-term working capital
- Second location buildout: points toward an SBA loan or commercial term loan
- Marketing push to fill a slow enrollment month: points toward a smaller working capital advance
Compare funding structures against your revenue pattern
Once the purpose is clear, weigh structures against how your revenue actually arrives — monthly auto-pay tuition behaves differently than event-based recital or tournament income. A business line of credit works well here because it's drawn only when needed, which suits a studio with predictable slow months rather than one single cash crunch.
- Match repayment frequency (daily, weekly, monthly) to your tuition collection schedule
- Avoid daily-debit products during months where enrollment is already down
- Confirm whether the lender reports to business credit bureaus, which matters for future terms
- Ask whether early payoff carries a penalty if enrollment rebounds faster than expected
Get your documentation ready before submitting
Most studio funding delays come from missing paperwork, not from the underwriting decision itself.
- Business bank statements (3-6 months)
- Profit and loss statement and balance sheet
- Lease agreement or proof of location
- Business license and any required instructor certifications
- Owner ID and, for SBA products, personal financial statement
Apply through a funding partner that understands studio revenue patterns
This is where a broker or consulting partner earns its place — not before you've mapped cash flow or cleaned up books, but once you know exactly what you need. Trifecta Business Group works through this exact process with studio owners, matching the funding structure to the enrollment calendar rather than pushing a single product. Reviewing options through the business funding options guide before applying gives you a baseline to compare offers against.
Build business credit so the next round is easier
Every funding decision either builds or ignores your studio's standalone credit profile. A studio that never separates personal and business credit ends up re-qualifying from scratch every time it needs capital.
- Open a business credit card used only for studio expenses
- Pay vendors (uniform suppliers, flooring installers) on terms and on time
- Keep utilization on any revolving line under 30%
- Request a small trade line increase every 6-12 months once payment history is established
Comparison: funding options for martial arts and dance studios
| Option | Best for | Key limitation |
|---|---|---|
| SBA loan | Second location or major build-out with long payoff runway | Slower approval, heavier documentation |
| Term loan | One-time equipment purchase (mats, mirrors, sound systems) | Fixed payment regardless of enrollment swings |
| Equipment financing | Mats, flooring, sound, or A/V upgrades specifically | Financing tied to the asset, not general cash needs |
| Business line of credit | Seasonal payroll gaps and recurring cash flow dips | Draw discipline required or it becomes a crutch |
| Merchant cash advance | Fast, short-term cash need with strong daily card volume | Higher effective cost, daily/weekly debits strain low months |
Studios with steady 12-month enrollment and a clear expansion plan tend toward an SBA loan or term loan. Studios managing month-to-month swings do better with a revolving line they can draw against only when needed — reviewing equipment financing separately from working capital keeps the two needs from getting mixed into one oversized loan.
Verdict: a martial arts or dance studio with predictable seasonal dips is usually better served by a business line of credit than a lump-sum term loan, reserving equipment financing strictly for mats, mirrors, and sound systems.
Common mistakes martial arts and dance studios make
- Borrowing a lump sum to cover a recurring problem. A single term loan doesn't fix a July-August enrollment dip that repeats every year — a revolving line matches the pattern better.
- Financing build-out and payroll with the same product. Mixing a one-time capital expense with ongoing cash flow needs makes it hard to track what the debt is actually paying for.
- Ignoring the lease term when picking a loan term. A 5-year buildout loan against a 3-year lease renewal creates a mismatch if the location doesn't renew.
- Taking a merchant cash advance against tuition auto-pay volume. Daily or weekly debits pulled against a studio's card processing can strain the exact slow months the studio was trying to cover.
- Skipping business credit building because the studio is small. Studios that never separate personal and business credit end up re-qualifying from scratch on every funding request, often at worse terms.
Get studio funding options reviewed
Talk through your enrollment cycle and funding needs with a specialist.
FAQ
What’s the best business loan for a martial arts studio?
A business line of credit best fits martial arts studios with seasonal enrollment swings, since it’s drawn only when tuition revenue dips. Equipment financing works better for a one-time mat, mirror, or flooring purchase.
Can a dance studio qualify for an SBA loan?
Yes, dance studios can qualify for SBA loans if they show steady time in business, clean financial statements, and a clear use of funds such as a second location or major build-out. SBA loans take longer to close than a term loan or line of credit.
How much does it cost to finance mats and mirrors for a studio?
Equipment financing costs vary by lender and the value of the equipment financed, so check current terms directly with a funding partner. The loan is typically secured by the equipment itself, which can lower the rate compared to unsecured working capital.
Is a merchant cash advance a good fit for a martial arts school?
A merchant cash advance can work for a fast, short-term need but daily or weekly debits against card volume can strain a studio during its slowest enrollment months. It’s best treated as a short bridge, not a recurring funding source.
How long does it take to get approved for studio funding?
Working capital and lines of credit can move in days once documentation is complete; SBA loans and larger term loans typically take longer due to added underwriting steps. Clean bookkeeping and ready bank statements are the biggest factor in approval speed.
What documents do martial arts studios need for a business loan?
Most lenders ask for 3-6 months of business bank statements, a profit and loss statement, lease agreement, business license, and owner ID. SBA loans additionally require a personal financial statement.
Should a studio finance equipment or use working capital for a build-out?
Equipment financing is built specifically for assets like mats, mirrors, and sound systems and keeps that debt separate from day-to-day cash flow. Working capital or a line of credit should stay reserved for payroll and operating gaps, not equipment purchases.
How do dance studios build business credit for better loan terms?
Opening a business credit card used only for studio expenses and paying equipment vendors on time builds a standalone credit profile separate from the owner’s personal credit. That history typically improves rates and approval speed on the next funding round.
One last thing
The studios that get the best terms aren't the ones with the highest enrollment — they're the ones that can produce 12 months of clean bank statements on request. Reviewing how to qualify for a working capital loan before you need the cash, not during the slow month, is what separates a fast approval from a rushed, worse-priced one.
Related guides
- Funding solutions for gyms and fitness studios
- Best short-term business loans for cash flow gaps
- How to build business credit for better loan terms
- How to choose the right funding option for business growth
- Best SBA loan programs for small businesses
What are you trying to fund?
Compare flexible working-capital options
Start with working capital and a line of credit, then compare payment structure and speed.
Compare options