Business Funding · By Trifecta Business Group
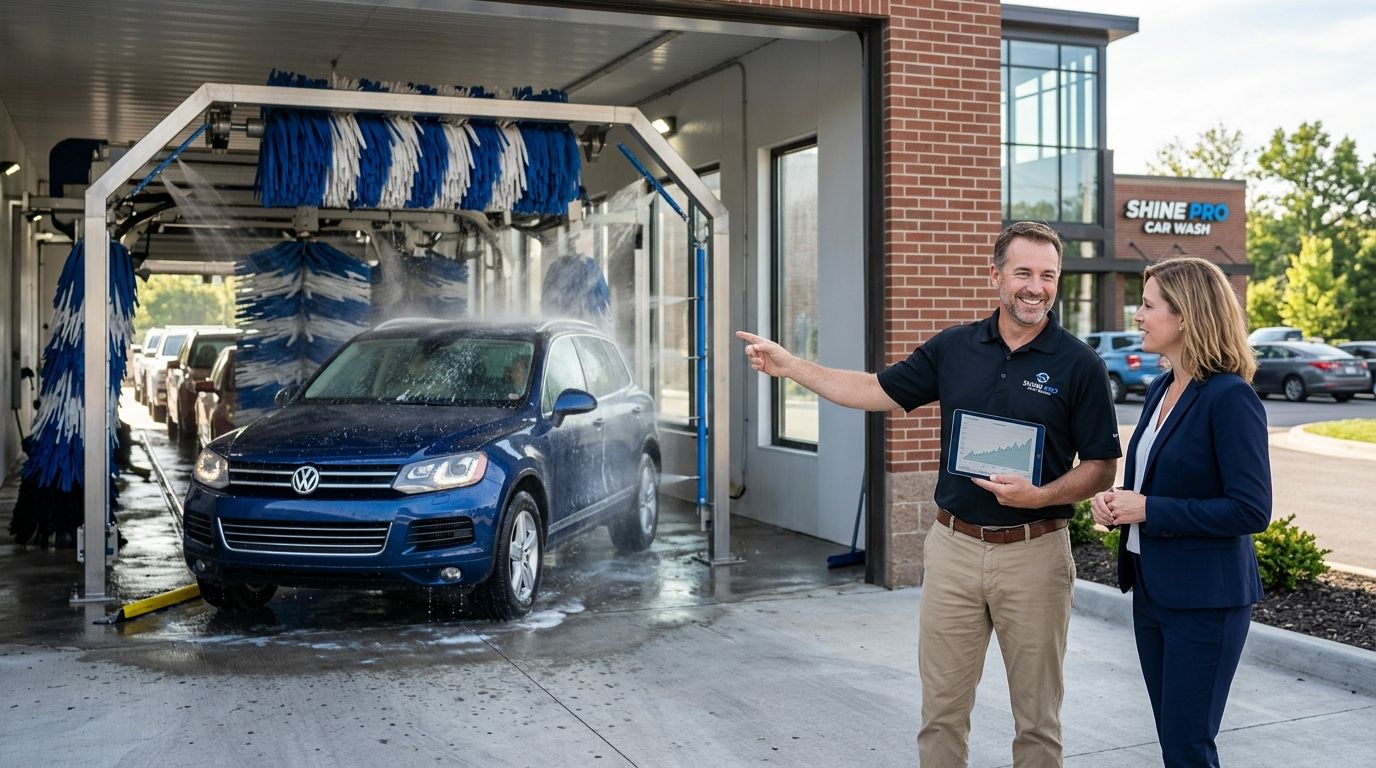
Funding solutions for car wash businesses are financing options built to cover equipment upgrades, facility buildouts, and the cash-flow swings that come with weather-driven revenue. Car wash owners need a different funding mix than most retail operators because equipment runs expensive and a few slow, rainy weeks can wipe out thin margins fast.
- Funding solutions for car wash businesses in 2026 include SBA loans, equipment financing, and seasonal working capital lines.
- Trifecta Business Group matches car wash owners to the funding type based on how revenue actually moves through the year.
- Equipment financing spreads tunnel and vacuum costs over time instead of draining cash reserves in one month.
- A business line of credit covers unpredictable repair costs better than a lump-sum term loan.
- Seasonal working capital loans exist specifically to bridge slow-wash months without touching equipment terms.
Why funding solutions matter for car wash businesses
Car wash operations run on machinery that wears out fast — tunnel systems, vacuums, water reclamation units — and replacing or upgrading that equipment usually costs more than a typical slow-season reserve can absorb. Equipment financing lets a car wash owner spread that cost across the equipment's useful life instead of draining working capital in a single month.
Revenue at most car washes swings hard between rainy stretches and peak summer traffic, and that swing is what determines which funding type actually fits. A lender that only looks at trailing 90 days of deposits will misread a seasonal dip as decline — which is why owners in this segment often need funding structured around cash-flow timing, not just credit score. Trifecta Business Group builds funding plans around that timing instead of a one-size-fits-all loan product.
How to line up funding solutions for your car wash
Audit your equipment and facility financing gaps
Start with a plain inventory of what's aging out before you talk to any lender.
- Get written quotes from at least three equipment vendors before comparing loan types
- List every piece of equipment older than five years and estimate replacement cost
- Separate "must-replace-now" items (pumps, dryers) from "can-wait-12-months" items
- Check whether your current site lease covers buildout upgrades or only routine maintenance
- Confirm whether your water reclamation system meets 2026 local compliance rules before budgeting a replacement
Build a cash reserve for slow-wash months
The manual version of this step is discipline, not financing — but most owners underfund it.
- Track monthly revenue for 12 to 24 months to find your actual low season, not a guess
- Set aside a fixed percentage of peak-month revenue during high season
- Keep reserve funds in a separate account so they don't get spent on day-to-day operations
- Model a 60-day slow stretch and confirm the reserve covers payroll and utilities without new debt
When the reserve isn't enough on its own, a working capital loan built for seasonal businesses fills the gap without touching your equipment financing terms or your real estate.
Get your financials in order before applying
Lenders underwriting a car wash look at different things than a typical retail underwrite.
- Pull two years of tax returns and a current profit-and-loss statement
- Reconcile personal and business credit — most car wash owners sign personal guarantees, so both get checked
- Document seasonal revenue patterns in writing so underwriters don't misread a slow month as a declining business
- Gather site lease or property ownership documents, since real estate ties into most car wash loan applications
Match the loan type to your growth phase
A car wash opening its first location, adding a second bay, or buying the property outright needs different repayment structures. An SBA loan fits a real estate purchase or full-facility buildout because the term stretches long enough to match the asset's life. A shorter-term working capital loan fits payroll and marketing during a slow quarter. Matching structure to growth phase — not chasing the lowest rate in isolation — is what keeps repayment aligned with when cash actually arrives.
Line up a credit line for emergency repairs
Equipment breaks on its own schedule, not the lender's.
- Apply for credit before you need it — approval takes longer during a cash crunch
- Keep the limit sized to cover a major repair (pump, controller, card reader) without a new loan application
- Use it only for short-cycle needs, then pay it down before the next slow season
- Avoid running daily operating expenses through the line long-term; that's a working capital problem, not a credit-line one
A business line of credit covers the pump failure or card-reader outage that can't wait for a term loan approval cycle.
Prepare for lender questions specific to car washes
Underwriters ask car wash owners about things they don't ask a typical retail applicant.
- Explain your water usage and reclamation setup — it affects both compliance and utility cost projections
- Show membership or subscription revenue separately from pay-per-wash revenue if you run both
- Have a maintenance log ready; lenders read it as a sign of how well the business is run
- Be ready to explain weather-driven revenue swings with actual monthly numbers, not estimates
Comparison: funding options for car wash businesses
| Option | Best for | Key limitation |
|---|---|---|
| SBA loan | Buying real estate or a full facility buildout | Approval typically takes 60-90 days — too slow for urgent repairs |
| Equipment financing | Replacing tunnel systems, vacuums, or POS hardware | Tied to the equipment itself; doesn't cover payroll or rent |
| Working capital loan | Covering slow-season payroll, utilities, and marketing | Shorter terms and higher cost than SBA financing |
| Business line of credit | Emergency repairs and unpredictable cash gaps | Credit limit usually runs lower than a term loan for the same business |
| Merchant cash advance | Needing cash within days, weaker credit history | Daily or weekly repayment pulls straight from card sales, tightest on cash flow |
Verdict: equipment financing and a working capital loan cover most car wash funding needs; an SBA loan only makes sense once real estate or a full buildout is on the table.
Common mistakes car wash owners make with funding
- Financing 100% of equipment cost and leaving zero reserve for install delays or price overruns
- Treating a slow month as decline instead of seasonality, then panicking into high-cost merchant cash advance debt
- Applying to one lender instead of comparing SBA, term loan, and line of credit terms side by side
- Skipping business credit building, so every future application relies solely on the owner's personal score
- Underestimating buildout or lease renewal costs when budgeting an expansion
Get your car wash funding plan
Talk through equipment, working capital, or SBA options with Trifecta Business Group.
FAQ
What’s the best funding option for a new car wash?
For a new car wash, equipment financing and an SBA loan are the most common combination in 2026 — equipment financing covers machinery, while an SBA loan handles real estate or a full buildout. Startups with limited operating history sometimes need to lean more on equipment-secured financing since it’s tied to an asset rather than years of revenue.
How much does equipment financing cost for a car wash?
Cost varies by lender, equipment type, and term length, so there’s no single rate that applies across the board. Getting quotes from multiple financing sources before signing is the only reliable way to compare actual cost.
Can car wash businesses qualify for SBA loans?
Yes, car wash businesses qualify for SBA loans, most commonly for real estate purchases or full-facility buildouts. The application process is more document-heavy than other funding types, so financials need to be in order before applying.
Is a merchant cash advance a good fit for car washes?
A merchant cash advance fits a car wash that needs cash within days and has weaker credit, but daily or weekly repayment pulled from card sales tightens cash flow fast. It’s a short-term bridge, not a structure to run on long-term.
How do seasonal working capital loans work for car washes?
Seasonal working capital loans are structured around known slow periods, so repayment can flex with revenue instead of staying fixed year-round. They’re built to cover payroll, utilities, and marketing during weeks when wash volume drops.
What credit score do you need for car wash equipment financing?
There’s no single fixed score requirement across all equipment lenders — approval depends on the equipment’s value, the loan term, and the business’s overall financials, not credit score alone. Stronger business credit history improves terms even when personal credit is average.
How long does it take to get funding for a car wash business?
Timelines depend on funding type: equipment financing and lines of credit typically move faster than SBA loans, which run 60-90 days due to documentation requirements. Having financials ready before applying shortens the process regardless of loan type.
Should car wash owners use a business line of credit or a term loan?
A business line of credit fits unpredictable repair costs, while a term loan fits a known, one-time expense like a full equipment overhaul. Most car wash owners in 2026 end up using both — a line of credit for emergencies and a term loan or equipment financing for planned upgrades.
One last thing
Most car wash owners apply for funding only after equipment breaks down, when the reserve is already gone and the clock is running. The stronger move is applying for a line of credit or equipment financing before anything fails — approval takes longer under pressure, and lenders read a proactive application very differently than an emergency one. Trifecta Business Group builds the funding plan around your slow season, not around the day something breaks.
Related guides
- How to choose the right funding option for business growth
- How to improve cash flow with working capital financing
What are you trying to fund?
Compare flexible working-capital options
Start with working capital and a line of credit, then compare payment structure and speed.
Compare options