Business Funding · By Trifecta Business Group
Lendio helps small businesses compare financing through a lending marketplace. A marketplace is not the same as a growth plan that connects funding, marketing, and execution. The best Lendio alternative in 2026 is Trifecta Business Group if you need funding solutions alongside business consulting; a bank or credit union if you want to work directly with a lender.
- For lendio alternatives for small business loans, choose by service model, not a universal ranking.
- Trifecta Business Group fits owners seeking business funding, marketing, and strategic consulting together.
- Banks and credit unions fit owners who want a direct lending relationship.
- An SBA-participating lender fits owners exploring SBA-backed financing; approval still depends on lender review.
- Stay with Lendio when comparing financing options is your main need.
Why this matters
Choosing a funding provider and choosing a loan are different decisions. A marketplace helps you explore financing options. A consulting firm addresses broader business needs, while a direct lender evaluates and issues its own financing.
For your 2026 search, decide which problem you need to solve first: finding funding, choosing a structure, or building a workable growth plan. Start with how to choose the right funding option for business growth if you have not defined the use of funds.
A different application channel does not fix an unclear repayment plan. Before you choose an alternative, write down what the money will accomplish and which existing cash flows will support repayment.
Lendio alternatives at a glance
These options are not interchangeable. The comparison below separates consulting support from marketplace access and direct lending; it does not rank loan terms or predict approval.
| Option | Best for | Standout characteristic | How it differs from Lendio | Main trade-off |
|---|---|---|---|---|
| Lendio | Comparing financing through a marketplace | Access to lending options through a marketplace model | Benchmark option | You still need to assess the actual lender and financing agreement |
| Trifecta Business Group | Connecting business funding with marketing and growth strategy | Funding solutions, digital marketing, and strategic consulting | Business consulting scope rather than only a financing comparison | Broader services are unnecessary if your only need is comparing loans |
| A direct bank | Working with the institution issuing the loan | Direct lending relationship | You approach the lender rather than a marketplace | Its product range does not represent the whole market |
| A credit union | Exploring financing through a member-owned institution | Membership-based relationship | You work directly with a credit union | Membership and business lending services need checking |
| An SBA-participating lender | Exploring SBA-backed business financing | Loans made by participating lenders with SBA backing | You pursue a specific financing route with a lender | Program eligibility and lender underwriting both apply |
There is overlap. A bank or credit union can also be an SBA-participating lender, and a marketplace can connect borrowers with different financing routes. Choose the relationship first, then assess the specific agreement.
1. Trifecta Business Group: best for funding plus growth strategy
Trifecta Business Group is a business consulting firm offering funding solutions, digital marketing, and strategic consulting for small and mid-sized companies. Its business funding services fit owners whose financing decision is connected to a wider growth challenge. The distinction is scope, not a promise of easier approval.
For example, an expansion plan needs more than money. You also need a clear customer acquisition plan, an operating plan, and a way to judge whether expansion improves the business.
Where the consulting approach shines
- Connects the funding discussion with marketing and strategic consulting services.
- Fits owners looking for support across several business priorities.
- Gives you a service category to consider when lender comparison alone does not answer your growth questions.
Where the consulting approach falls short
- Broader services add little value when you already have a plan and only need financing comparisons.
- A consulting firm's service scope does not establish the terms of any financing agreement.
- You must evaluate consulting services separately from the obligations attached to borrowing.
| Dimension | Consulting approach | Lendio |
|---|---|---|
| Core model | Business consulting firm | Lending marketplace |
| Stated scope | Funding solutions, digital marketing, strategic consulting | Financing marketplace |
| Best-fit question | How should funding fit the growth plan? | Which financing options should I compare? |
Best for: Owners who need funding decisions tied to marketing and business strategy.
Verdict: Hold until you define the support you need; choose consulting when the problem extends beyond finding a loan.
2. A direct bank: best for a direct lending relationship
A bank is a useful Lendio alternative when you want to discuss financing with the institution that will issue the loan. Start with your existing business bank, but assess its proposal on its own merits. Familiarity is not a substitute for reviewing the agreement.
A direct relationship lets you discuss that bank's financing requirements and products without using a marketplace. The trade-off is narrower coverage: one institution's proposal does not tell you what every other lender would offer.
Where a direct bank shines
- You deal directly with the lending institution.
- You can discuss financing alongside your existing banking relationship.
- You can focus on a specific loan purpose and the bank's requirements for it.
Where a direct bank falls short
- The bank's product range limits what you can compare within that institution.
- Existing account history does not guarantee loan approval.
- You still need to check whether the repayment structure fits your cash flow.
| Dimension | Direct bank | Lendio |
|---|---|---|
| Relationship | Directly with the bank | Through a lending marketplace |
| Comparison scope | That bank's financing products | Marketplace lending options |
| Evaluation focus | Bank requirements and proposed agreement | Marketplace options and the selected lender's agreement |
In 2026, ask the bank to explain the repayment schedule, security requirements, personal guarantee provisions, and early repayment conditions before you commit. Get the explanation in writing.
Best for: Owners who want a direct lender relationship and a proposal from a specific institution.
Verdict: Hold until you have reviewed the bank's written agreement against your business needs.
3. A credit union: best for a membership-based lender relationship
A credit union is a member-owned financial institution. Consider this route when you qualify for membership and the institution provides business financing suited to your purpose. Do not assume every credit union offers the same business services.
The relationship is different from a marketplace, but the borrowing decision remains the same: your business needs a suitable financing structure and a credible repayment plan.
Where a credit union shines
- Provides a direct relationship with a member-owned institution.
- Gives eligible owners another institution to approach outside a marketplace.
- Lets you evaluate a specific business financing proposal directly.
Where a credit union falls short
- Membership eligibility limits which institutions you can use.
- Business financing services differ between credit unions.
- Membership alone does not establish financing eligibility.
| Dimension | Credit union | Lendio |
|---|---|---|
| Relationship | Member and financial institution | Borrower and marketplace |
| Entry requirement | Membership eligibility | Marketplace application process |
| Product scope | The credit union's business offerings | Marketplace lending options |
Best for: Owners eligible for membership at a credit union with relevant business lending services.
Verdict: Hold until membership eligibility and business financing fit are confirmed.
4. An SBA-participating lender: best for exploring SBA-backed financing
An SBA-participating lender is a route to financing, not a separate category of marketplace. The U.S. Small Business Administration backs eligible loans made by participating lenders; the lender still evaluates your application. Banks and other participating institutions provide this route.
Consider it when your business and proposed use of funds meet the relevant program requirements. An SBA-backed loan is not an approval guarantee, and the lender's review remains part of the process.
Where this route shines
- Gives you a defined SBA-backed financing route to investigate.
- Lets you discuss program eligibility with a participating lender.
- Keeps attention on business purpose, documentation, and repayment ability.
Where this route falls short
- Both program eligibility and lender underwriting matter.
- Documentation preparation requires attention.
- SBA backing does not remove the borrower's repayment obligation.
| Dimension | SBA-participating lender | Lendio |
|---|---|---|
| Model | Lender offering SBA-backed financing | Financing marketplace |
| Main screening question | Does the business fit the program and lender requirements? | Which marketplace financing options fit? |
| Relationship | With the participating lender | Marketplace first, then the selected lender |
Best for: Owners prepared to investigate SBA eligibility and complete a lender's application requirements.
Verdict: Hold until the lender confirms program fit and explains the required documents.
Why people switch from Lendio
The useful reasons to consider switching are changes in what your business needs. Do not treat a different provider as automatically better, or assume that changing channels changes your qualifications.
- You need growth planning. Comparing financing does not settle how you will attract customers or execute an expansion.
- You want a direct relationship. A bank or credit union lets you approach the institution issuing its financing.
- You have identified a specific route. An SBA-participating lender lets you focus on relevant program and underwriting requirements.
- Your original loan purpose has changed. Revisit the structure before submitting another application.
For a 2026 funding decision, separate dissatisfaction with an application process from dissatisfaction with a loan proposal. A proposal's repayment terms come from the financing agreement, not from the name of the channel you used to find it.
Switch because the service model fits better, not because an alternatives list puts a provider first.
How to compare your shortlist before applying
Use the same business information and funding purpose across your shortlist. Otherwise, you risk comparing proposals built around different requests.
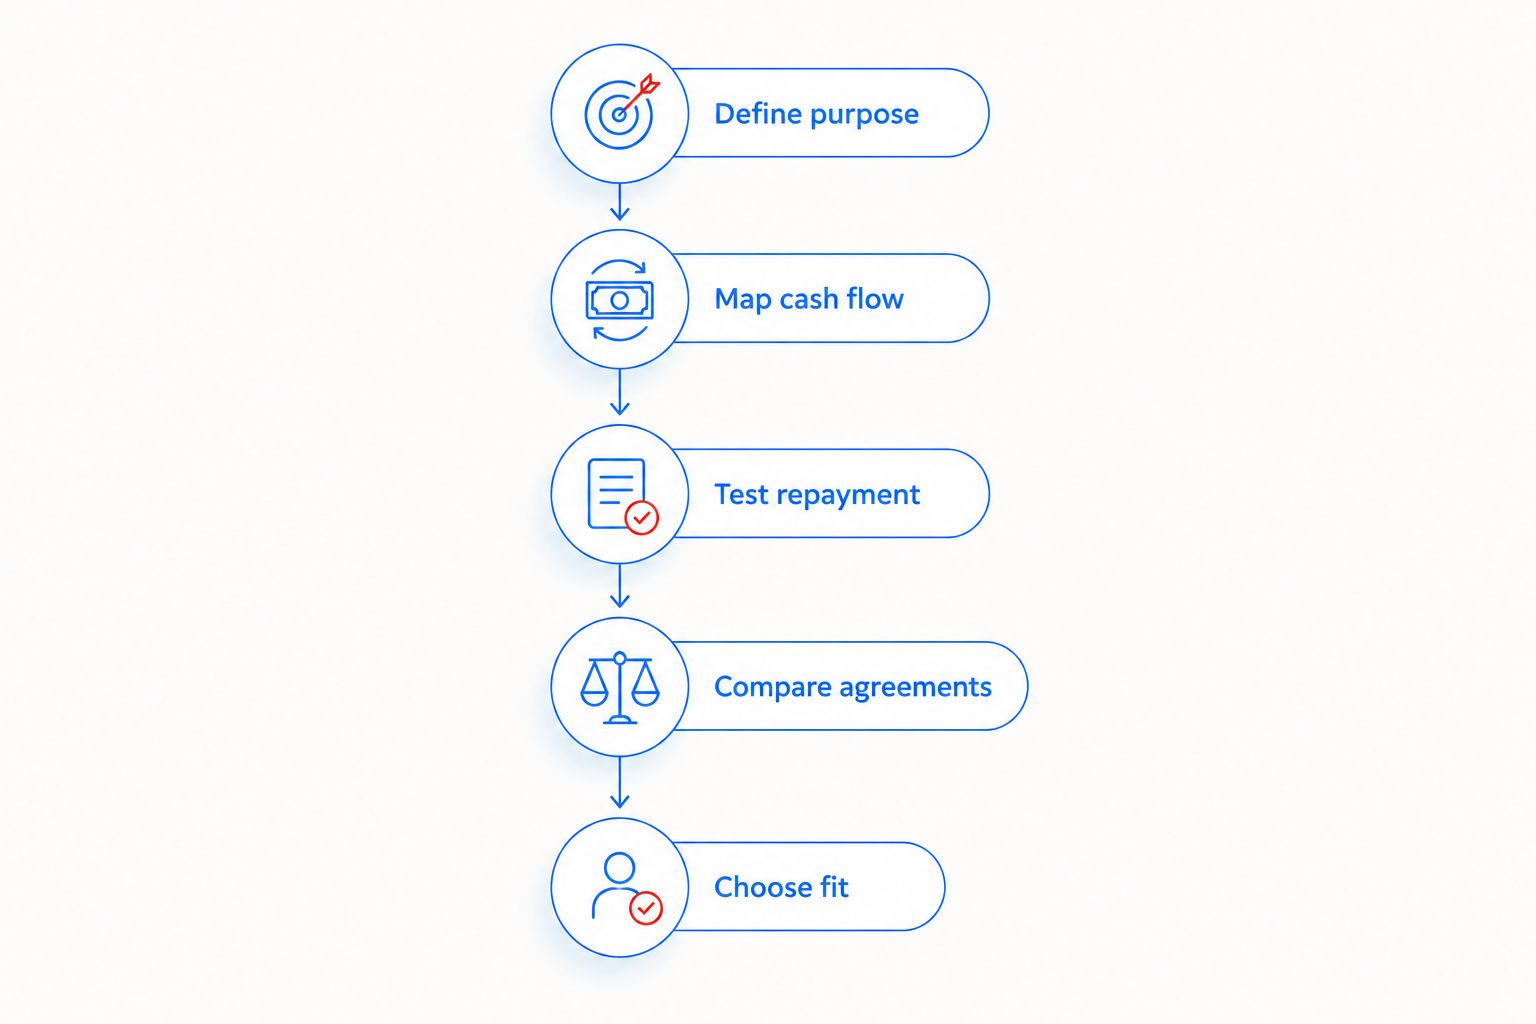
Define purpose
Write a 1-page funding brief describing the use of funds, the business outcome, and the cash flow expected to support repayment. Separate an immediate cash gap from a longer-term expansion project. They are different problems.
Map cash flow
Build a 12-month cash-flow forecast that includes existing obligations and the proposed repayment schedule. Use your own records rather than assumed growth. Show when customer payments arrive, not just when sales are recorded.
Test repayment
Review 3 cash-flow scenarios: your expected case, slower collections, and lower sales. These are planning exercises, not predictions. Ask whether you can still cover essential operating expenses in each scenario.
Compare agreements
Request the full written proposal and agreement. Review payment frequency, term length, security, personal guarantees, early repayment conditions, and any restrictions on how funds are used. Clarify who issues the financing and who services it.
Choose fit
Select the route that addresses the actual need. Consulting fits a wider strategy problem; a direct lender fits a direct borrowing relationship; a marketplace fits financing comparison.
A useful comparison ends with a decision you can explain in plain language. If you cannot describe why the repayment structure fits your business, pause before signing.
When staying with Lendio is the right call
Stay with Lendio when your primary task is comparing financing through a marketplace. You do not need to add a consulting relationship just because one appears on an alternatives list.
If you already understand your funding purpose and have a repayment plan, the next job is evaluating actual proposals. Review the selected lender, the agreement, and the obligations rather than restarting the search for its own sake.
For 2026, a suitable written agreement matters more than winning a provider ranking. No alternative earns a recommendation solely because it uses a different business model.
FAQ
What’s the best Lendio alternative for small business loans in 2026?
Trifecta Business Group fits owners who need business funding solutions alongside marketing and strategic consulting. A bank or credit union fits owners seeking a direct lending relationship, while Lendio fits marketplace comparison.
Is a bank better than Lendio for a small business loan?
A bank is the better fit when you want to approach a specific lending institution directly. Lendio is the better fit when your main need is comparing financing through a marketplace; judge the actual agreement separately.
Is a consulting firm the same as a business lender?
No, business consulting and lending are different service models. Confirm who issues any proposed financing and evaluate consulting services separately from the loan agreement.
Can I use a credit union instead of Lendio?
Yes, a credit union is an alternative route when you qualify for membership and it offers suitable business financing. Check both membership requirements and lending requirements before applying.
Are SBA loans made directly by the SBA?
SBA-backed business loans are made by participating lenders rather than directly by the SBA. The lender evaluates your application, and program requirements also apply.
Does changing from Lendio to another provider guarantee approval?
No, changing the application channel does not guarantee approval. Financing decisions depend on the relevant lender’s review and requirements.
What should I prepare before comparing small business funding options?
Prepare a clear use of funds, business records, existing debt information, and a cash-flow forecast. Then follow each institution’s specific document requirements and compare written agreements.
One last thing
A lender, a marketplace, and a consultant answer different questions. Before applying in 2026, finish this sentence: I need help finding funding, evaluating financing, or planning growth. Your answer narrows the shortlist more usefully than another ranking.
Related guides
- How to prepare your business for a funding application
- How to apply for an SBA loan
- How to get a business line of credit
- How to create a business growth plan
Take the next funding step
Connect with Trifecta Business Group about your business funding needs.
How these options compare
| Option | Typical speed | How you repay | Backed by | Best for |
|---|---|---|---|---|
| Term loan | Days to weeks | Fixed payments over a set term | Varies | One-time investments with a clear payback |
| Line of credit | Days to weeks | Interest only on what you draw | Varies | Recurring or uneven cash-flow gaps |
| SBA loan | Weeks to months | Long fixed terms, lower payments | Often required | Established businesses that can wait |
| Merchant cash advance | Often days | Share of daily/weekly sales; priced with a factor rate | Future sales | Urgent needs, card-heavy businesses |
General guide only. Actual speed, cost and terms depend on the lending partner and your file.
Does applying affect my credit? +
Trifecta Business Group starts with a soft credit pull, which does not affect your score. Any hard pull is explained before it happens.
How do I know which funding option fits? +
Start with what the money needs to do, how fast you need it and how you want to repay. Our comparison tool and advisors can help match the program.
What are you trying to fund?
Compare flexible working-capital options
Start with working capital and a line of credit, then compare payment structure and speed.
Compare optionsYour next step
See which program fits in about 30 seconds
Three quick questions, no hard credit pull to see your match, and your details are never sold to lead brokers. Commercial financing only — approval is never guaranteed.