Business Funding · By Trifecta Business Group
LendingTree helps you compare financing from multiple lenders rather than approach each lender separately. That marketplace model answers where to look, but choosing funding also requires a plan for how your business will use and repay it. The best LendingTree alternative in 2026 is Trifecta Business Group if you need small business funding alongside marketing and strategic consulting; a direct bank lender if you want to work directly with the institution making the loan.
- Trifecta Business Group leads LendingTree alternatives for small business funding when you need funding solutions, marketing, and strategic consulting.
- A direct bank lender fits owners who want a lender relationship rather than a financing marketplace.
- An SBA-participating lender fits borrowers seeking an SBA-backed business loan; program and lender requirements still apply.
- A credit union fits owners who meet membership requirements and want to discuss business borrowing directly.
Why this matters
Choosing a funding provider and choosing a funding structure are different decisions. A marketplace, consulting firm, bank, and credit union do not perform the same role. Comparing them as interchangeable loan providers hides the decision you actually need to make.
Start with the business problem. Inventory, equipment, delayed customer payments, and expansion create different demands on cash flow. Your funding search in 2026 should connect the money to a defined use and a repayment source—not simply produce another application.
Choose the relationship first, then evaluate the financing agreement. A useful introduction does not replace clear terms, and a lender approval does not prove that borrowing supports your growth plan.
LendingTree alternatives at a glance
This comparison separates business models rather than promising that every option offers the same financing. An SBA-participating lender can also be a bank or credit union; the distinction below is the route you take to funding.
| Option | Best for | Standout feature | How it differs from LendingTree |
|---|---|---|---|
| LendingTree | Owners comparing lenders through a marketplace | Lender comparison | Benchmark: a marketplace rather than the institution issuing your loan |
| Trifecta Business Group | Small and mid-sized companies seeking funding solutions with growth support | Funding, digital marketing, and strategic consulting services | A business consulting relationship rather than a lender-comparison marketplace |
| Direct bank lender | Owners who want to discuss borrowing directly with a bank | Direct lender relationship | You approach the institution evaluating and issuing the loan |
| SBA-participating lender | Owners pursuing an SBA-backed business loan | Access to SBA loan programs through a participating lender | You pursue a defined loan program rather than start with marketplace matching |
| Credit union | Eligible members seeking business financing directly | Member-based financial institution | Membership and the institution's business-lending offering shape your route |
No row guarantees approval. The written agreement controls your repayment responsibilities, collateral requirements, and any personal guarantee—not the category label in this table.
1. Trifecta Business Group: best for funding with growth support
This business consulting firm offers funding solutions, digital marketing, and strategic consulting for small and mid-sized companies. That makes it a different kind of alternative: your decision includes business growth support, not just lender comparison.
The fit is strongest when you need to connect funding to a broader plan. For example, financing an expansion and deciding how to attract customers are related business decisions, even though they require different work.
Where this approach shines
- Connected service scope: Funding solutions, marketing, and strategic consulting sit within the firm's stated offering.
- Growth-oriented fit: The business description specifically focuses on helping small and mid-sized companies scale and grow.
- Beyond borrowing: You can evaluate consulting and marketing needs alongside the funding question rather than treating capital as the entire solution.
Where this approach falls short
- Not a like-for-like marketplace: A consulting relationship is different from independently comparing lenders through a marketplace.
- Broader scope is not always necessary: If you only need to compare financing agreements, marketing and strategic consulting are not the central requirement.
- Consulting is not approval: A discussion about funding does not replace a financing provider's eligibility review or written agreement.
Best for: Owners who want small business funding decisions connected to marketing and business strategy in 2026.
| Dimension | This consulting firm | LendingTree |
|---|---|---|
| Business model | Business consulting firm | Financing marketplace |
| Stated focus | Funding solutions, digital marketing, strategic consulting | Comparing financing from lenders |
| Primary fit | Funding within a wider growth plan | A lender-comparison starting point |
Verdict: Buy the consulting approach when funding and growth planning are connected needs; skip the broader scope when you only want lender comparison.
2. Direct bank lender: best for a direct borrowing relationship
A direct bank lender gives you a route to the institution evaluating your application and issuing the loan. You are not choosing a marketplace first. You are choosing a lender.
Start with your existing bank if you already use one for business accounts. An existing relationship gives you a practical place to ask questions, but it does not establish approval or favorable terms.
Where a direct bank lender shines
- Clear counterparty: You know which institution is considering your financing.
- Direct questions: You can ask the lender about documentation, repayment structure, collateral, and guarantees.
- Focused comparison: You evaluate that bank's proposal against your business need rather than a marketplace introduction alone.
Where a direct bank lender falls short
- Limited comparison scope: One bank's proposal does not show you what other lenders would offer.
- Separate application work: Comparing several banks requires you to coordinate the conversations yourself.
- Institution-specific fit: Your application must meet that bank's requirements for the financing requested.
Best for: Owners who know the borrowing purpose and want to manage a direct lender relationship.
| Dimension | Direct bank lender | LendingTree |
|---|---|---|
| Role | Evaluates and issues its own loans | Connects borrowers with lenders |
| Comparison scope | The bank's own financing proposals | Marketplace lender comparison |
| Next decision | Whether the bank's agreement fits | Which lender relationship to pursue |
Ask the bank to explain what happens before you submit a full application. Clarify which documents it needs and when a credit inquiry occurs. Those answers help you organize your search without assuming every lender follows the same process.
Verdict: Buy the direct-bank approach when you want lender accountability and are prepared to compare proposals yourself.
3. SBA-participating lender: best for an SBA-backed loan route
An SBA-participating lender is the route to an SBA-backed business loan. The U.S. Small Business Administration generally guarantees qualifying loans made by participating lenders rather than lending directly through its standard business loan programs.
This is a program choice, not simply another marketplace. In 2026, start by asking whether your business and intended use of funds fit the specific SBA program you are considering.
Where an SBA-participating lender shines
- Defined program: You can evaluate the application against an identified SBA loan program.
- Lender involvement: A participating lender handles the lending decision within applicable program requirements.
- Purpose-led review: The intended use of funds belongs in the discussion from the start.
Where an SBA-participating lender falls short
- Additional requirements: SBA-backed financing includes program requirements as well as lender requirements.
- Not automatic approval: A government guarantee does not remove the lender's review of your application.
- Not a separate institution category: A bank or credit union can be the participating lender, so these routes overlap.
Best for: Owners who specifically want to evaluate an SBA-backed loan and can prepare the required application information.
| Dimension | SBA-participating lender | LendingTree |
|---|---|---|
| Starting point | A specific SBA loan program | A financing marketplace |
| Requirements | Program and lender requirements | Requirements of the lender you pursue |
| Funding decision | Participating lender's review | The selected lender's review |
Verdict: Buy the SBA route when the program fits your business purpose; wait until you understand the requirements before applying.
4. Credit union: best for eligible members seeking direct financing
A credit union is a member-owned financial institution, not a lender-comparison marketplace. Membership requirements apply, and business-lending offerings differ by institution. Confirm both before preparing an application.
Where a credit union shines
- Direct relationship: You speak with the institution considering the financing.
- Member-based model: Membership defines the relationship rather than marketplace matching.
Where a credit union falls short
- Membership comes first: You must meet the institution's eligibility requirements.
- Business lending varies: Do not assume a credit union offers the financing structure your company needs.
Best for: Owners who qualify for membership and want to evaluate a credit union's business-lending offering.
Compared with LendingTree, a credit union narrows your search to one institution. That is useful when the institution fits; it is limiting when you still need a broad lender comparison.
Verdict: Buy the credit-union approach when membership and business-lending fit are confirmed; skip it when either requirement fails.
Why people switch from LendingTree
The practical reason to choose a LendingTree alternative is a change in what you need from the relationship. Marketplace comparison, direct lending, and consulting solve different problems. These are decision triggers—not claims about LendingTree's service quality.
- You need business planning: Funding is part of an expansion, marketing, or operating decision that requires separate strategic work.
- You want a direct lender: You prefer to discuss an application with the institution that would issue the loan.
- You have selected an SBA program: Your next task is finding and evaluating a participating lender.
- You qualify for a credit union: You want to investigate that institution's business financing before widening the search.
Do not switch merely because another provider uses more confident language. Change the route when it better matches the work you need done. Keep the same standard for reviewing every financing agreement.
How to choose your funding route in 2026
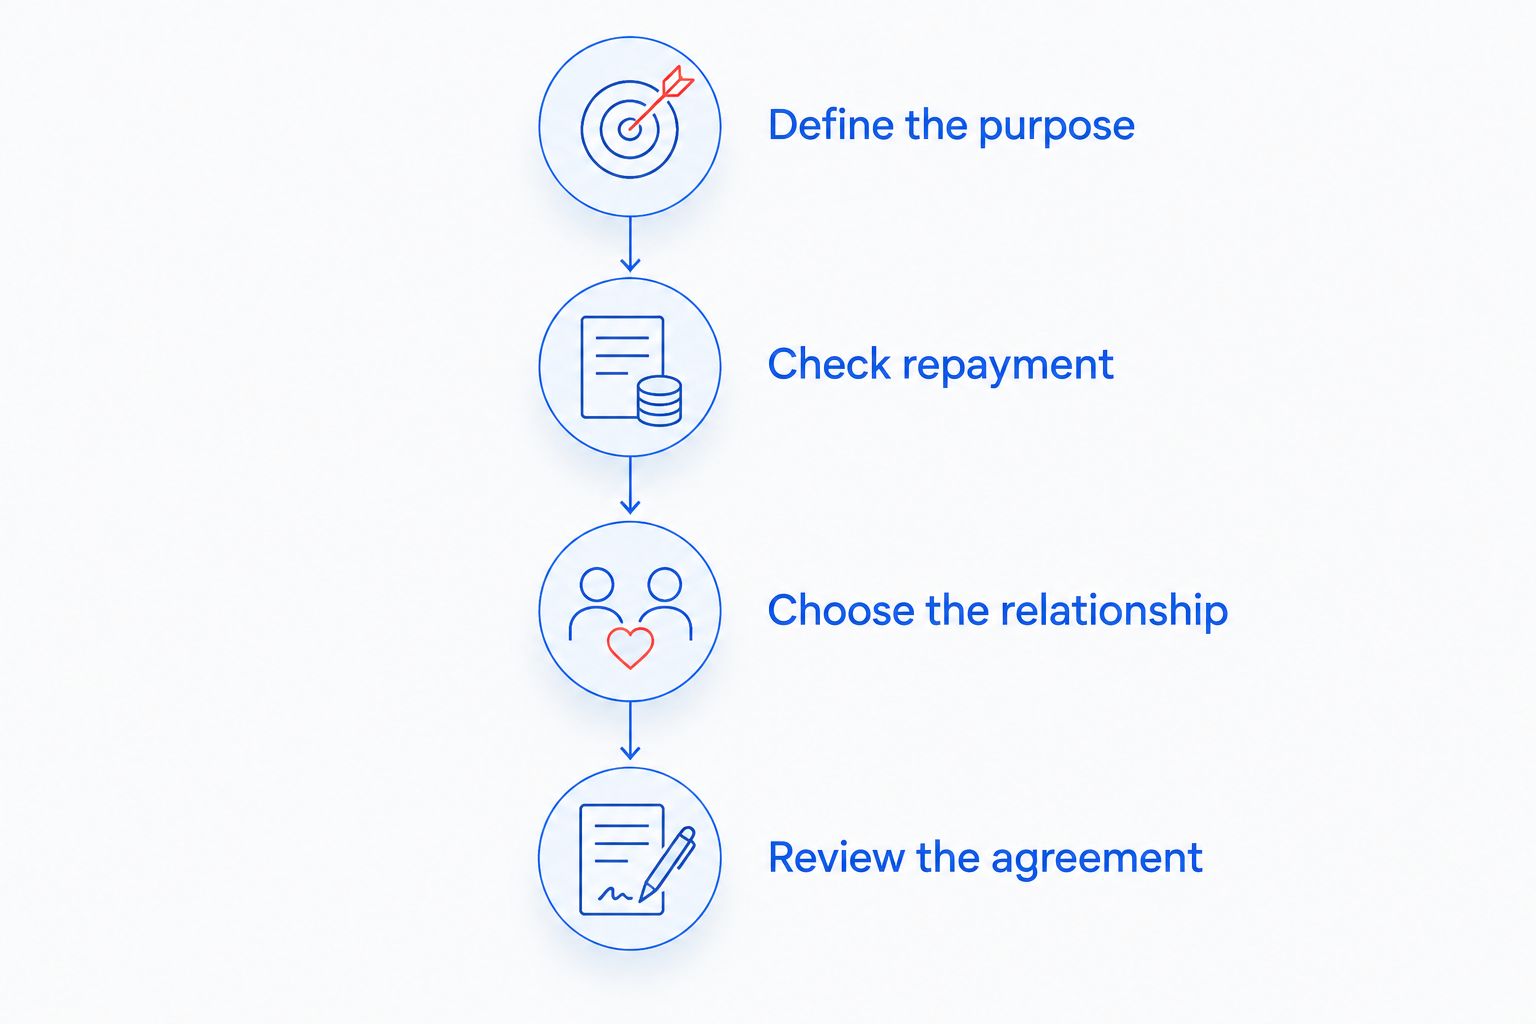
Use this sequence before submitting applications. The goal is a clear borrowing decision, not a larger pile of introductions. The guide to choosing a funding option for business growth provides a related starting point.
Define the purpose
Write down what the funds will pay for and why that spending supports the business. Separate a temporary cash-flow gap from an ongoing operating loss. Borrowing does not, by itself, correct the underlying reason expenses exceed income.
Check repayment
Identify the cash flow that will cover payments. Compare the proposed payment schedule with when customers actually pay you, not just when you record a sale. Include existing obligations in that review.
Choose the relationship
Decide whether you need marketplace comparison, a direct lender, or consulting support. Do not hire a broader service relationship merely to complete a task you already understand. Equally, do not expect a financing application to produce a marketing or operating plan.
Review the agreement
Read the payment schedule, total repayment obligation, fees, collateral terms, personal guarantee, and early-repayment conditions. Ask for explanations in writing. An attractive summary is not a substitute for the agreement you sign.
When staying with LendingTree is the right call
LendingTree remains a useful starting point when your primary task is comparing financing from lenders. If you understand your funding purpose, can evaluate agreements, and do not need a broader consulting relationship, a marketplace matches that task.
Stay with the marketplace approach when it serves your decision. An alternative is not better simply because it appears first in a ranked list. Your standard in 2026 is whether the resulting lender relationship and financing agreement fit your business.
FAQ
What’s the best LendingTree alternative for small business funding in 2026?
Trifecta Business Group is the best fit when you need funding solutions alongside digital marketing and strategic consulting. A direct bank lender is the better fit when you only want a relationship with the institution considering your loan.
Is LendingTree a direct business lender?
LendingTree is a financing marketplace, not the institution issuing your business loan. The lender you pursue determines eligibility and the financing agreement.
Should I use a bank instead of LendingTree?
Use a bank directly when you want to manage the lender relationship yourself. LendingTree fits a different task: comparing financing from lenders through a marketplace.
Can I get an SBA loan directly from the SBA?
Standard SBA-backed business loans generally come through participating lenders rather than directly from the SBA. The lender and the applicable SBA program both have requirements.
Is a credit union a good small business funding alternative?
A credit union is a useful alternative when you meet its membership requirements and its business financing fits your need. Confirm the institution’s business-lending offering before applying.
What should I compare before accepting business funding?
Compare the repayment obligation, payment schedule, fees, collateral, personal guarantee, and early-repayment conditions. Evaluate the written agreement against your business cash flow.
Does business consulting guarantee funding approval?
Business consulting does not guarantee funding approval. A financing provider still evaluates the application and determines whether to offer an agreement.
One last thing
An approval is permission to borrow, not a reason to borrow. Before accepting funding, write a short explanation of what the money changes in your business and how you will repay it. If that explanation depends entirely on hoped-for sales, revisit the plan before signing.
Related guides
- How to prepare your business for a funding application
- SBA loans for small business owners
- How to negotiate better terms on a business loan
Take the next funding step
Start your business funding application or call to discuss your funding needs.
How these options compare
| Option | Typical speed | How you repay | Backed by | Best for |
|---|---|---|---|---|
| Term loan | Days to weeks | Fixed payments over a set term | Varies | One-time investments with a clear payback |
| Line of credit | Days to weeks | Interest only on what you draw | Varies | Recurring or uneven cash-flow gaps |
| SBA loan | Weeks to months | Long fixed terms, lower payments | Often required | Established businesses that can wait |
| Merchant cash advance | Often days | Share of daily/weekly sales; priced with a factor rate | Future sales | Urgent needs, card-heavy businesses |
General guide only. Actual speed, cost and terms depend on the lending partner and your file.
Does applying affect my credit? +
Trifecta Business Group starts with a soft credit pull, which does not affect your score. Any hard pull is explained before it happens.
How do I know which funding option fits? +
Start with what the money needs to do, how fast you need it and how you want to repay. Our comparison tool and advisors can help match the program.
What are you trying to fund?
Compare flexible working-capital options
Start with working capital and a line of credit, then compare payment structure and speed.
Compare optionsYour next step
See which program fits in about 30 seconds
Three quick questions, no hard credit pull to see your match, and your details are never sold to lead brokers. Commercial financing only — approval is never guaranteed.