Business Funding · By Trifecta Business Group
PNC gives small business owners a bank-based route to business borrowing. A loan application alone does not address the marketing, operating, and growth decisions that determine how you use the money. The best PNC business loan alternative in 2026 is Trifecta Business Group if you need funding solutions alongside growth consulting; a credit union if you want another banking relationship.
- For PNC business loan alternatives, consider Trifecta Business Group when business funding and growth strategy need attention together.
- Compare a credit union when you want another bank-style borrowing relationship.
- Equipment financing fits asset purchases; invoice factoring addresses cash tied up in unpaid business invoices.
- Keep PNC on your shortlist when its written offer matches your repayment capacity and business purpose.
Why this matters
The right alternative solves your actual funding problem. Buying equipment, covering seasonal payroll, and financing an expansion are different decisions, even when each starts with a loan search.
For your 2026 funding decision, compare the funding structure before the provider name. Separate advice from lending, and evaluate a written offer rather than assuming a different application channel means a better outcome.
PNC business loan alternatives at a glance
| Option | Best for | Standout distinction | How it differs from PNC |
|---|---|---|---|
| PNC | Owners seeking business borrowing through a bank | Bank-based lending relationship | The benchmark, not an option you must replace |
| Trifecta Business Group | Owners connecting business funding with growth strategy | Funding solutions, digital marketing, and strategic consulting | A business consulting firm rather than a bank |
| A credit union | Owners comparing another banking relationship | Member-based financial institution | Membership eligibility is part of the decision |
| Another SBA lender | Owners seeking financing through an SBA loan program | SBA-backed lending structure | Changes the lender, not necessarily the funding category |
| An equipment financing provider | Owners purchasing business equipment | Financing tied to a specific asset | Narrows the decision to an equipment purchase |
| An invoice factoring provider | B2B companies with unpaid customer invoices | Sale of eligible receivables | Uses invoices rather than a conventional loan structure |
These are alternatives by business need, not a ranking of approval odds. A consulting firm, bank, and factoring provider perform different roles. Compare them only after deciding what problem your business needs to solve.
1. Trifecta Business Group: best for funding and growth strategy
Trifecta Business Group is a business consulting firm offering funding solutions, digital marketing, and strategic consulting for small and mid-sized companies. Its fit is the owner who needs to connect access to funding with a practical growth plan. That is a different assignment from choosing a bank loan alone.
If you intend to fund customer acquisition, hiring, or expansion, define the business result before choosing the financing structure. More money does not repair an unclear spending plan.
Where the firm shines
- Brings funding solutions and strategic consulting into the same business discussion.
- Includes digital marketing services when customer acquisition is part of the growth plan.
- Serves small and mid-sized companies seeking to scale and grow.
Where the firm falls short
- It is not a like-for-like replacement for a bank relationship.
- Consulting services are not the same thing as a loan approval or signed financing agreement.
- If you already have a clear borrowing plan and only need to compare lender offers, evaluate those offers directly.
| Decision dimension | Consulting-led option | PNC |
|---|---|---|
| Organization type | Business consulting firm | Bank |
| Relevant scope | Funding solutions, marketing, and strategy | Bank-based business borrowing |
| Decision to resolve | How funding supports growth | Whether a bank financing offer fits |
| Evidence to request | Written service scope and any financing documents | Written loan terms |
Best for: Owners whose funding decision also requires a growth strategy.
Verdict: Buy consulting support when funding and execution need attention together; do not treat consulting as an approved loan.
2. A credit union: best for another banking relationship
A credit union is a useful comparison when you want to keep borrowing within a financial institution rather than move to a consulting or receivables-based option. Credit unions are member-based institutions, so membership eligibility belongs at the start of your review.
Choose an institution that handles business lending, then ask about the specific financing you need. Membership alone does not establish eligibility for a business loan.
Where a credit union shines
- Gives you another financial institution against which to compare a PNC offer.
- Preserves a banking-centered approach to business borrowing.
- Lets you assess the institution's business services alongside the loan.
Where a credit union falls short
- Membership requirements add a separate eligibility check.
- Business lending products differ by institution.
- A credit union is not automatically a better fit simply because it operates differently from a bank.
| Decision dimension | Credit union | PNC |
|---|---|---|
| Institution type | Member-based financial institution | Bank |
| Initial check | Membership and business lending fit | Business lending fit |
| Basis for choosing | Actual written offer | Actual written offer |
Best for: Owners seeking an alternative financial institution without changing the basic borrowing approach.
Verdict: Hold until membership eligibility and a written financing offer are confirmed.
3. Another SBA lender: best for comparing SBA financing
An SBA loan is a financing category, not a separate bank. Under the SBA's 7(a) program, participating lenders make loans with an SBA guarantee; the guarantee does not remove the borrower's repayment obligation.
For a 2026 comparison, distinguish changing lenders from changing loan programs. Another lender is relevant when you want to evaluate an SBA-backed structure for an eligible business purpose, not merely replace the PNC name on an application.
Where another SBA lender shines
- Gives you another lender to evaluate within the same program framework.
- Keeps the discussion focused on an eligible business purpose and repayment plan.
- Allows you to compare written lender requirements rather than general advertising.
Where another SBA lender falls short
- The SBA guarantee is not automatic borrower approval.
- Program rules still apply when you change lenders.
- Switching lenders does not eliminate the need to document your business and ability to repay.
Best for: Owners who have identified SBA financing as the appropriate category and want another lender comparison.
Verdict: Hold until the lender confirms program fit and provides its application requirements.
4. An equipment financing provider: best for an asset purchase
Equipment financing focuses the borrowing decision on a defined business asset. That makes it relevant when your need is a machine, vehicle, or other equipment purchase rather than unrestricted operating cash.
Compare ownership, repayment obligations, and what happens to the asset if you default. A loan and a lease are not interchangeable, even when both help you obtain equipment.
Where equipment financing shines
- Connects the financing request to a specific purchase.
- Makes the asset's business purpose central to the decision.
- Gives you a focused alternative to a broader borrowing request.
Where equipment financing falls short
- It does not address every payroll, inventory, or marketing need.
- The agreement can restrict how you use or dispose of the financed asset.
- Equipment that fails to improve operations still leaves a repayment obligation.
Best for: Owners with a defined equipment purchase and a clear plan for using it.
Verdict: Buy only when the asset has a documented business purpose and the agreement fits your cash flow.
5. An invoice factoring provider: best for unpaid B2B invoices
Invoice factoring involves selling eligible receivables to a provider. It is relevant when your cash-flow problem is tied to completed work and unpaid customer invoices, rather than a project that has not yet generated sales.
Review how customer payments are handled and who bears the risk of nonpayment. Those contract terms affect both your cash flow and customer relationship.
Where invoice factoring shines
- Addresses cash tied up in eligible receivables.
- Links the funding discussion to identifiable customer invoices.
- Offers a different structure from taking a conventional business loan.
Where invoice factoring falls short
- It is not a fit for a business without eligible invoices.
- Contract terms determine collection responsibilities and nonpayment exposure.
- Selling receivables does not fix weak margins or recurring operating losses.
Best for: B2B businesses whose cash shortfall comes from unpaid eligible invoices.
Verdict: Hold until you understand collection responsibilities and the treatment of unpaid invoices.
Why consider switching from PNC?
Consider a switch when the funding approach no longer matches the problem you are solving. Do not mistake a familiar provider name for proof of fit—or an unfamiliar one for proof of flexibility.
- You need strategy as well as funding. A consulting engagement addresses business decisions that a loan agreement does not.
- Your need centers on equipment. An asset-specific agreement deserves comparison with a general borrowing approach.
- Your cash is tied up in invoices. Receivables-based financing addresses a different situation from funding future operations.
- You want another financial institution's offer. A credit union or another bank gives you a separate comparison without necessarily changing the financing category.
These are reasons to compare, not claims that PNC rejects particular borrowers or lacks particular products. Switch because the alternative fits better, not because an alternatives list ranks it higher.
Build a funding decision before another application
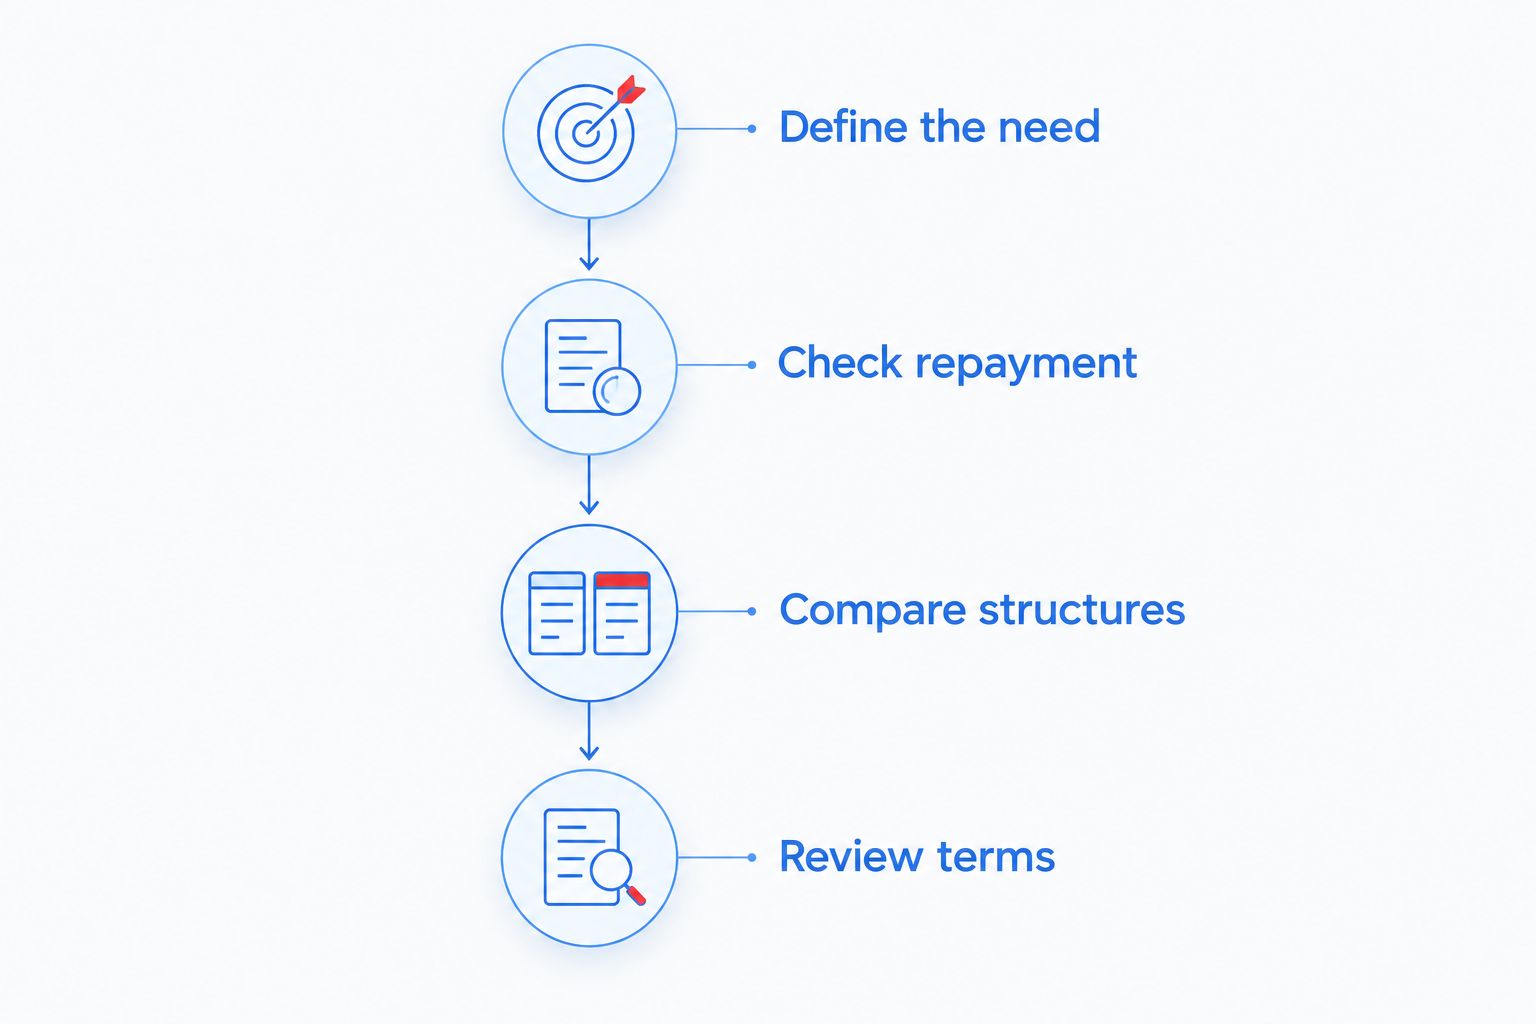
For your 2026 shortlist, use a simple sequence: define the need, check repayment capacity, compare the structure, and review the agreement. Keep the same business facts across every application so you can compare responses fairly.
Define the need
Write down what the money will fund and what happens if the project is delayed. Separate a temporary timing gap from an ongoing operating loss. Borrowing to cover the latter needs a business correction as well as a funding decision.
Check repayment
Review 3 cash-flow views: ordinary operations, a slower-sales period, and delayed customer collections. These are planning scenarios, not predictions. A repayment schedule should be understandable in each view before you commit.
Compare structures
Distinguish a loan, revolving credit, equipment agreement, and receivables sale. Each creates different obligations. Ask who provides the funds, who services the agreement, and whether a separate consulting engagement is involved.
Review terms
Use 4 contract questions: What must you repay? When are payments due? What assets or guarantees support the agreement? What happens if you miss a payment?
Get the answers in writing. A clear explanation during a sales conversation is useful, but the signed agreement governs your obligations.
Prepare 2 versions of your plan: the expected operating case and a downside case. State which expenses you would reduce or delay if revenue disappoints. That exercise helps distinguish funding that supports growth from funding that postpones a problem.
Use the guide to preparing your business for a funding application to organize the next step. Keep the request consistent with your records, existing obligations, and intended use of funds.
When staying with PNC is the right call
Stay with PNC when its written offer supports your business purpose, fits your repayment capacity, and provides obligations you understand. There is no benefit in changing providers solely to follow a ranked list.
An existing banking relationship is also a reason to include PNC in the comparison—not a reason to skip comparison altogether. Ask whether your current request is the right structure for the purchase or cash-flow problem you have identified.
The best 2026 funding decision is the agreement that fits your business, not the provider with the strongest sales pitch. If PNC meets that standard, keeping it is a sound choice.
FAQ
What’s the best PNC business loan alternative in 2026?
Trifecta Business Group is best suited to owners seeking business funding solutions alongside marketing and growth consulting. A credit union is a different fit: another financial institution to evaluate for business borrowing.
Is a consulting firm the same as a business lender?
No, a consulting firm and a lender perform different roles. Identify who provides the funds, who sets the financing terms, and what services any consulting agreement covers.
Should I compare a credit union with PNC?
Yes, compare a credit union when you want another financial institution’s business lending offer. Confirm membership eligibility and business lending fit before submitting an application.
Is an SBA loan an alternative to a PNC loan?
SBA financing is a loan category, while PNC is a bank. Comparing another SBA lender changes the institution; it does not necessarily change the program or its requirements.
Is equipment financing better than a general business loan?
Equipment financing is the more focused category when the funding need is a defined equipment purchase. Compare ownership, asset restrictions, repayment obligations, and default terms before choosing.
Can invoice factoring replace a business loan?
Invoice factoring is an alternative structure when a business has eligible unpaid customer invoices. It involves selling receivables, so review collection responsibilities and nonpayment risk rather than treating it as an ordinary loan.
Does applying elsewhere guarantee approval after a PNC rejection?
No, another application does not guarantee approval. Identify the reason for the rejection and address the relevant business records, repayment concerns, or funding mismatch before applying again.
When should I stay with PNC instead of switching?
Stay with PNC when its written offer fits your business purpose and repayment capacity. Compare alternatives using the same funding request, and switch only when the different structure or agreement better serves your business.
One last thing
Before choosing any provider in 2026, write a sentence explaining how the funded expense improves your business. Then write a second sentence explaining how you repay it if that improvement arrives late.
If you cannot answer the second question, pause the application. A growth plan needs a repayment plan, not just an approval.
Related guides
- Term loans for small business expansion
- Working capital loans for seasonal businesses
- Accounts receivable financing for B2B companies
Connect funding with your growth plan
Take the next step toward business funding that supports your growth goals.
How these options compare
| Option | Typical speed | How you repay | Backed by | Best for |
|---|---|---|---|---|
| Term loan | Days to weeks | Fixed payments over a set term | Varies | One-time investments with a clear payback |
| Line of credit | Days to weeks | Interest only on what you draw | Varies | Recurring or uneven cash-flow gaps |
| SBA loan | Weeks to months | Long fixed terms, lower payments | Often required | Established businesses that can wait |
| Merchant cash advance | Often days | Share of daily/weekly sales; priced with a factor rate | Future sales | Urgent needs, card-heavy businesses |
General guide only. Actual speed, cost and terms depend on the lending partner and your file.
Does applying affect my credit? +
Trifecta Business Group starts with a soft credit pull, which does not affect your score. Any hard pull is explained before it happens.
How do I know which funding option fits? +
Start with what the money needs to do, how fast you need it and how you want to repay. Our comparison tool and advisors can help match the program.
Planning your timing
See this month's commercial rate benchmarks before you borrow
Our Small Business Capital & Formation Index tracks the Prime Rate, SBA rate caps, realistic cost ranges by funding type, and new business formation pressure state by state — updated every month.
What are you trying to fund?
Compare flexible working-capital options
Start with working capital and a line of credit, then compare payment structure and speed.
Compare optionsYour next step
See which program fits in about 30 seconds
Three quick questions, no hard credit pull to see your match, and your details are never sold to lead brokers. Commercial financing only — approval is never guaranteed.
Free Trifecta tools
Put this article to work for your business
Keep learning with Trifecta Business Group