Business Funding · By Trifecta Business Group
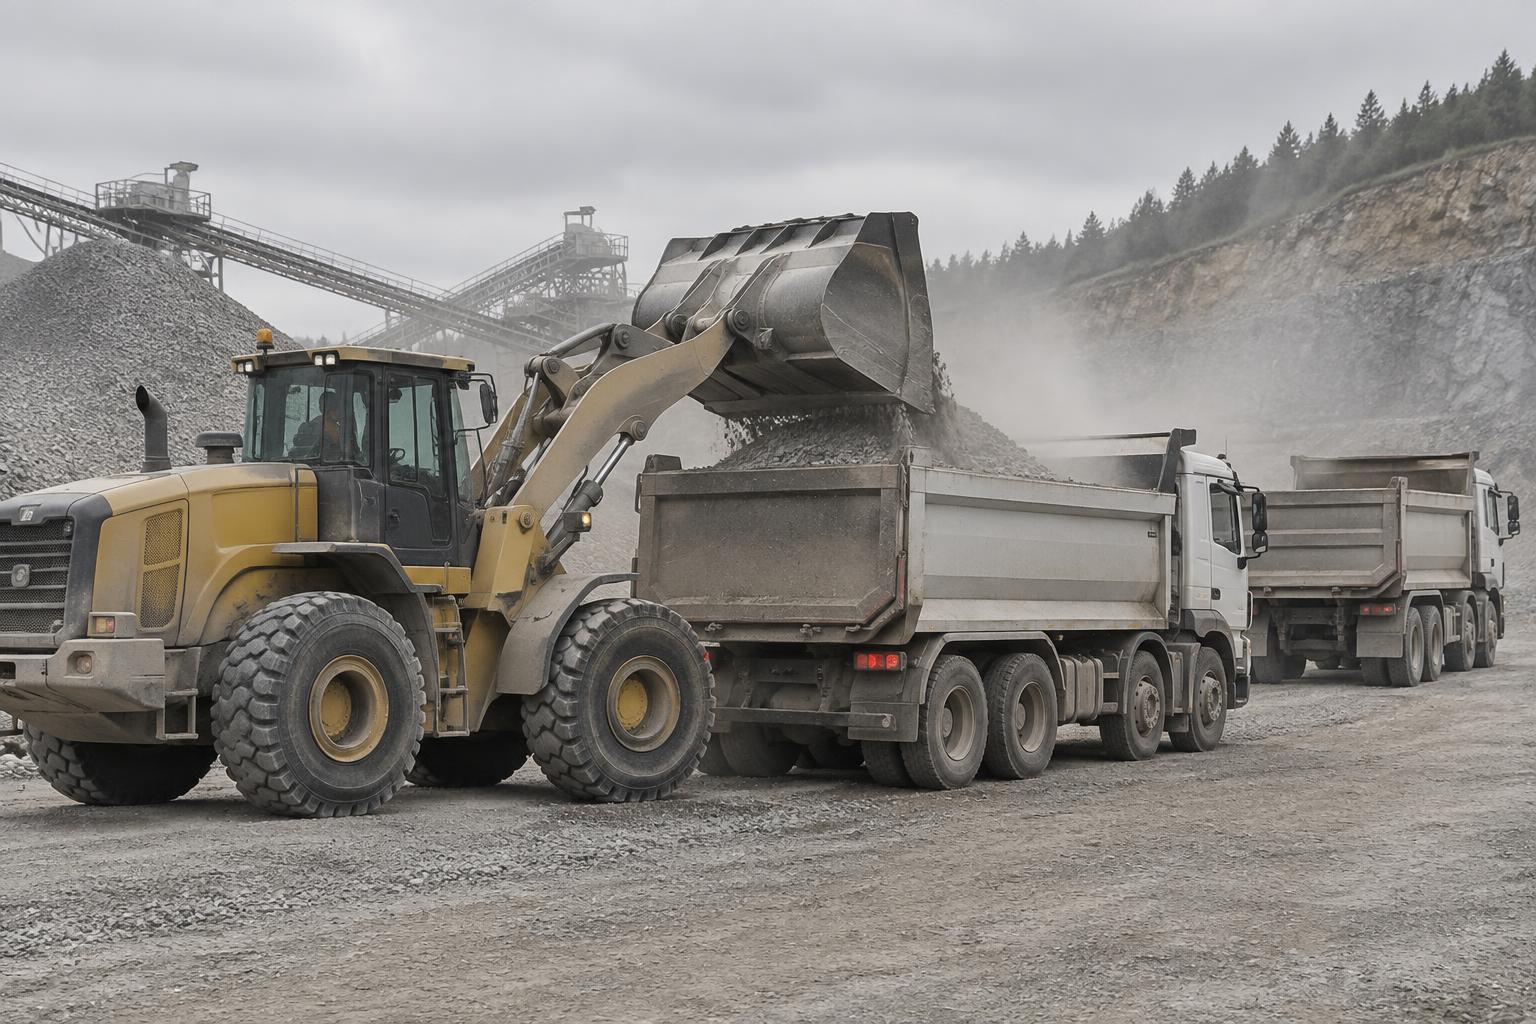
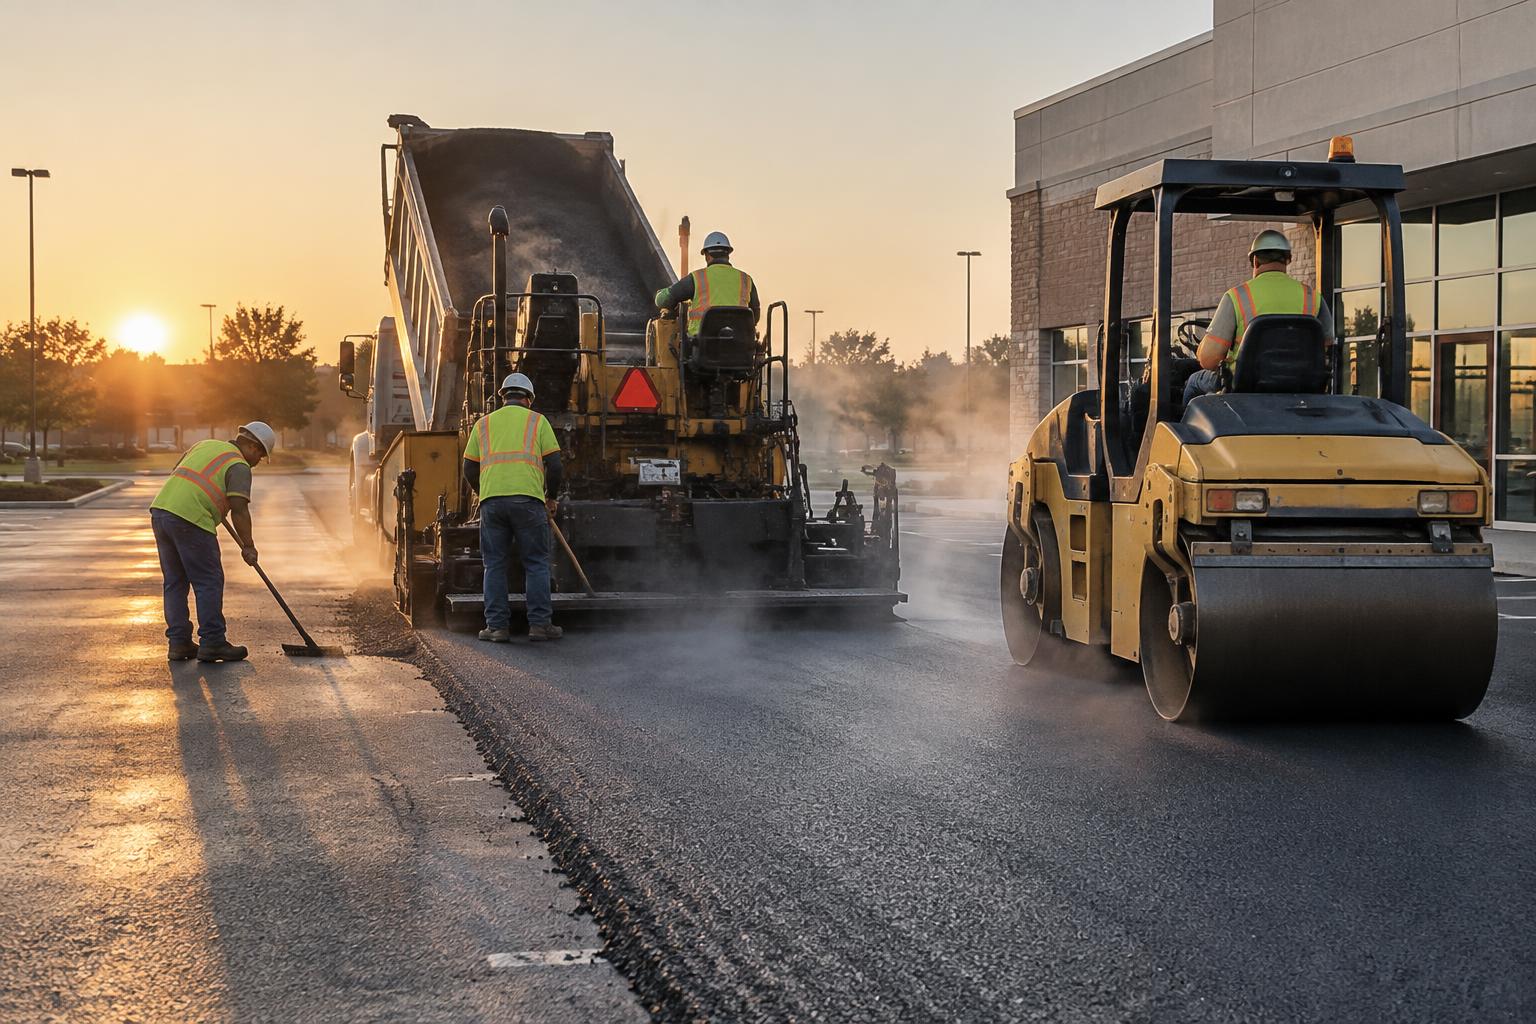
Paving is a cash-hungry trade. A paver, a roller and a few trucks cost more than many contractors bill in a quarter, materials are paid for up front, and the season can end before the last invoice clears. This guide covers how asphalt and paving contractors finance equipment and cash flow, and what lenders want to see.
Financing pavers, rollers, milling machines and trucks
Heavy paving equipment is usually financed with the machine as collateral, which keeps payments tied to an asset that holds resale value.
- Equipment financing: fixed payments for new or used pavers, rollers, skid steers, milling machines, sealcoating rigs and dump trucks.
- Equipment refinancing: turns equity in machines you already own into cash for repairs or the down payment on the next unit.
- Seasonal or step payments: some programs can set lower payments in winter months and higher ones in season. Availability depends on the program.
Ask for a written quote showing the total of all payments, not just the monthly number. Our equipment financing page explains how the desk works, and the free tools hub has a payment calculator you can run without giving contact details.
Covering mobilization before the first draw
On commercial and municipal work, asphalt, fuel, crew payroll and equipment rental come due weeks before the first draw is paid. Retainage can hold back part of every invoice until the job closes.
- Working capital: a lump sum to cover materials and payroll at the start of a job. See working capital options.
- Receivables funding: advances cash against approved invoices or pay applications from creditworthy general contractors and agencies. See how invoice factoring works.
- Business line of credit: draw for each job and repay when it pays. Lines usually need more time in business and steadier deposits than term loans.
Our free MobilizeIQ calculator on the construction financing page estimates how much cash a job ties up before it pays, so you can size what you need before you ask.
Planning for the off-season
Paving revenue drops in cold months in much of the country, but loan payments, insurance and key employees don’t stop.
- Build a winter reserve during peak months, and avoid stacking short-term advances late in the season.
- Time equipment purchases so the first payments land when work is coming in, where the program allows.
- If you take card payments on residential driveway jobs, check what processing really costs you. Our payment processing review is free.
What lenders look at for a paving business
- Time in business and, for public work, bonding history.
- Bank deposits: three to six months of statements, read alongside your seasonality. Expect to explain a slow January.
- Credit: the owner’s personal credit and existing equipment payments.
- Contracts and receivables: signed contracts, pay applications and an aging report help for receivables funding.
- Equipment details: year, make, model, hours and a dealer quote or bill of sale.
If a bank turned you down, our free Translate-IQ tool explains a decline letter in plain terms, and a statement review shows how your deposits read to an underwriter.
How Trifecta works with paving contractors
Trifecta Business Group is a commercial loan brokerage based in Glen Allen, VA, serving contractors nationwide. One dedicated advisor matches your file to one wholesale lending desk at a time, based on that desk’s underwriting criteria. Your file is never auctioned or sent to a call center.
There’s no hard credit pull to explore your options, and approval is never guaranteed; terms and timing depend on the program and the lender. The intake takes about 3 minutes, plus a separate document upload. For current rate benchmarks, including the Wall Street Journal Prime Rate (7.00% as of October 2026), see the Small Business Capital Index.
Ready to size your next job or machine? Start your application.
Does applying affect my credit? +
Trifecta Business Group requires no hard credit pull, which does not affect your score. Any hard pull is explained before it happens.
How do I know which funding option fits? +
Start with what the money needs to do, how fast you need it and how you want to repay. Our comparison tool and advisors can help match the program.
Planning your timing
See this month's commercial rate benchmarks before you borrow
Our Small Business Capital & Formation Index tracks the Prime Rate, SBA rate caps, realistic cost ranges by funding type, and new business formation pressure state by state — updated every month.
What are you trying to fund?
Compare flexible working-capital options
Start with working capital and a line of credit, then compare payment structure and speed.
Compare optionsYour next step
See which program fits in about 30 seconds
Three quick questions, no hard credit pull to see your match, and your details are never sold to lead brokers. Commercial financing only — approval is never guaranteed.
Free Trifecta tools
Put this article to work for your business
Keep learning with Trifecta Business Group