Auto Repair Shop Financing
A repair shop may need a new lift, diagnostic equipment or operating cash while fleet and warranty invoices are outstanding. Those needs are different from offering a customer a payment option for a repair.

 BBB profile &
Chamber member
Trifecta Business Group separates commercial financing for your shop from payment processing review and customer-financing enrollment. One advisor matches the file to one lending desk at a time; the file is never sold or auctioned. There is no hard credit pull to explore your options. Commercial financing only. Approval is never guaranteed, and timing depends on the program and the lender.
01 · Auto Repair Shop FinancingLifts, Alignment Racks and Scan Tools
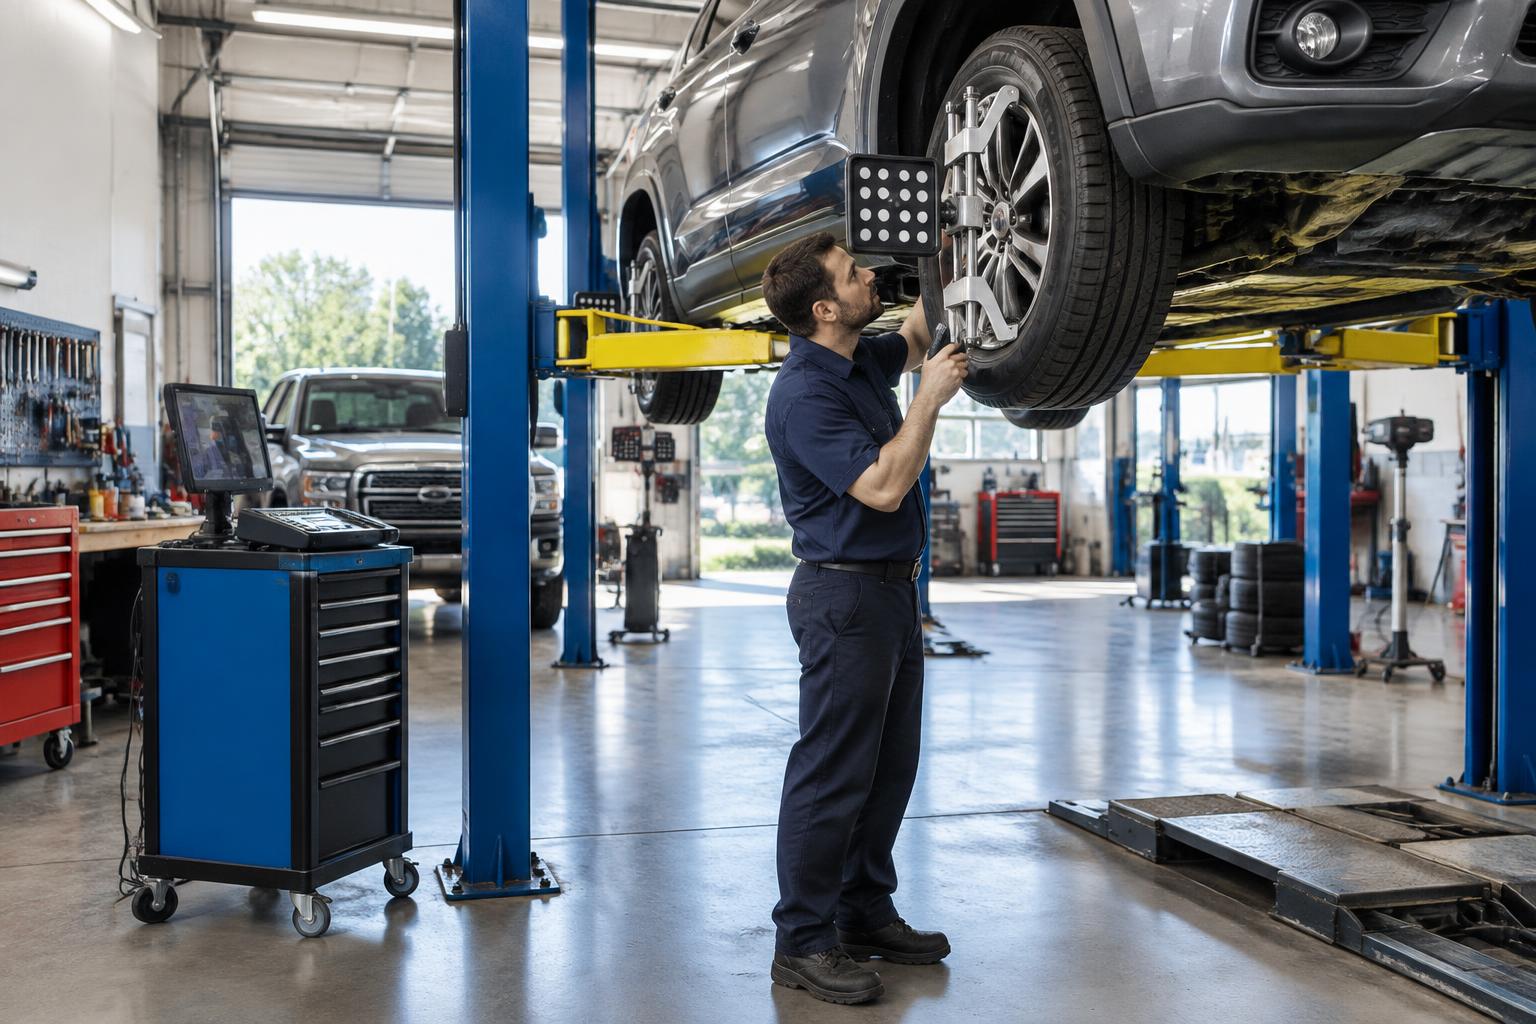
Equipment financing may support commercial lifts, alignment racks, diagnostic scanners, tire equipment and other business-use tools. Review considers the asset, vendor, condition, useful life and shop finances. Used equipment may need inspection or valuation. Include serial numbers and itemize software subscriptions, installation and training rather than assuming all costs qualify together.
Compare a purchase loan with lease ownership and end-of-term provisions. Budget for electrical work, floor preparation, calibration and downtime during installation. Expected additional repair volume is a forecast, not guaranteed revenue. A payment should be evaluated against cash flow after payroll, rent, parts and existing obligations. Equipment condition and resale value do not replace a review of the business.
Bring a vendor quote, scope of installation and current equipment financing details. Ask what happens if the asset needs repair or must be replaced during the term. Our equipment financing page explains the broader distinction between loans and leases; available terms require individual review.
Working Capital When Fleet and Warranty Work Pays Slow
Fleet contracts and warranty work can produce receivables while technicians and parts suppliers still need payment. Build a cash calendar using actual invoice approval and collection practices. Include disputed claims, deductions, parts returns and the cost of rework. A billed repair is not automatically an approved or collectible invoice.
Commercial working capital may be considered for operating expenses, while eligible business receivables may support a different structure. Explain which customers pay on terms and which repairs are paid at completion. Financing does not solve recurring losses or make unprofitable work profitable. Compare the payment schedule with slower collections, seasonal demand and the cash needed for existing obligations.
Prepare recent business bank statements, current financials, outstanding invoices and a debt schedule. Describe the business expense and the period the cash gap covers. Your advisor reviews product and state restrictions before discussing a suitable option. Use secure upload for sensitive records; later credit inquiries follow their own authorization process.
Card Processing Review
A payment processing statement review is separate from a financing application. It looks at how card payments, fees and settlement arrangements work for your shop. Bring a complete processing statement and explain your mix of card-present, phone and online payments. Refunds, chargebacks and service needs are part of the review.
Compare total processing cost and contract terms rather than one advertised rate. Ask about equipment, software integration, settlement timing, termination provisions and support. Any proposed change depends on your statements and business needs; savings and service outcomes are not guaranteed. A processing review does not imply loan approval or give a customer a credit offer.
Keep financing and processing decisions distinct so each can be assessed on its own terms. Do not provide account passwords or full customer card data in a general inquiry. The payment processing page explains the statement-review path; contact Trifecta if you need help identifying the appropriate business records.
Customer Financing for Big Repairs
For eligible repair services, a separate customer payment program may let your business present payment options to customers facing a larger bill. This information is for repair shop owners considering enrollment, not a consumer credit offer from Trifecta. Business and service eligibility, customer applications and payment terms require separate review.
Explain the repairs you perform, typical service scope and how you present written estimates. Customers should understand price, financing terms and any applicable disclosures before proceeding. Do not promise acceptance, a specific monthly payment or when your shop will receive funds. Customer financing is not working capital for your business and does not replace collecting payment under the agreed service terms.
Visit the customer financing page for the separate enrollment link, or call 1.877.977.3015 to discuss your shop. For commercial equipment or operating funds, use the application and secure document upload below. One advisor matches the file to one lending desk at a time. Approval is never guaranteed, and timing depends on the program and the lender.
Start your commercial financing application
About 3 minutes, plus upload. One advisor, one lending desk at a time; the file is never sold or auctioned. Approval is never guaranteed, and timing depends on the program and the lender.
Or call 1.877.977.3015.
Questions, Answered
Used commercial lifts, alignment racks and diagnostic equipment may be considered based on condition, value and business finances. Bring a vendor quote and asset details. Inspection or valuation may be needed. Approval is never guaranteed, and timing depends on the program and the lender.
Commercial working capital or eligible receivables funding may address a timing gap, subject to review. Explain invoice approval, disputes and collection practices. Compare payment obligations with payroll and parts costs under a slower collection scenario; financing does not make an unprofitable repair contract profitable.
No. Processing review is a separate assessment of statements, payment arrangements and contract costs. Any proposed changes depend on your business and current setup. Savings are not guaranteed, and reviewing processing does not establish eligibility, approval or terms for a commercial financing request.
No. Customer payment programs are separate from financing for your shop equipment or operating expenses. Eligible businesses enroll, while customers apply under separate terms. This page addresses business owners, not a consumer credit offer. Customer approval, payment terms and business eligibility are not guaranteed.
There is no hard credit pull to explore your options. A later inquiry requires separate authorization. One advisor matches the file to one lending desk at a time; the file is never sold or auctioned. Commercial financing only; state and product restrictions may apply.