Business Funding · By Trifecta Business Group
SBA loan approval has no single turnaround time in 2026: your lender’s review, the SBA processing route, and the transaction’s requirements determine the schedule. Approval is not the same as funding—you still need to satisfy closing conditions before the lender releases money. Ask for a timeline from a complete application to disbursement, not just an estimate for an SBA response.
- How long does SBA loan approval take? The lender, processing route, and closing requirements determine your timeline.
- SBA approval does not mean your business can immediately use the funds.
- Track application completion, underwriting, SBA processing, closing, and disbursement separately.
- Trifecta Business Group offers business funding and strategic consulting for small and mid-sized companies.
Why this matters
A loan timeline affects more than paperwork. If you are buying a business, replacing equipment, or covering an expansion, the date that matters is when funds become usable—not when someone says the application looks promising.
Start with the broader requirements for SBA loans for small business owners, then ask your lender which requirements apply to your transaction. A general program description cannot establish your closing date.
For your 2026 funding plan, separate the deadline you want from the deadline the lender can support. Do not make a nonrefundable commitment based solely on an estimated approval date.
How long does SBA loan approval take?
Your SBA loan timeline runs through 5 milestones: application completion, lender underwriting, SBA processing, closing, and disbursement. Each milestone answers a different question. Treating them as a single approval event hides the work still outstanding.
| Milestone | What happens | What you should confirm |
|---|---|---|
| Application completion | You submit the information the lender needs to review the request | Has the lender accepted the file as complete? |
| Lender underwriting | The lender evaluates eligibility, repayment ability, and the proposed transaction | What questions or conditions remain? |
| SBA processing | The applicable SBA authorization or guaranty process takes place | Is the lender using delegated authority or submitting for SBA review? |
| Closing | Required documents, signatures, and transaction conditions are addressed | What prevents the loan from closing? |
| Disbursement | The lender releases funds under the loan’s requirements | When and how will the money become usable? |
The starting point matters. An estimate measured from a complete application does not include the time you spend collecting records, correcting financial statements, or supplying missing ownership information.
The endpoint matters just as much. A lender’s credit decision, an SBA authorization, and a funded loan are different outcomes. Ask which outcome an advertised turnaround describes before using it in your business plan.
Application completion
Your application is ready for review when the lender has the required information—not simply when you submit an online form. Request the lender’s document checklist and identify who confirms that the file is complete.
Keep a record of that confirmation. If the lender requests additional information later, ask whether the request changes the expected decision date or addresses a condition needed for closing.
Lender underwriting
Underwriting is the lender’s assessment of whether your business and proposed use of funds meet its requirements. The review can involve financial records, existing debts, ownership details, and explanations of unusual business results.
Answer the actual question raised. Sending another spreadsheet without explaining the difference between it and your earlier submission leaves the lender with more information but no clearer answer.
SBA processing
The lender’s processing authority affects how SBA requirements are handled. Certain participating lenders have delegated authority to make specified decisions without a separate SBA credit review for each eligible loan.
Delegated authority does not remove the lender’s underwriting responsibilities. Ask the lender to identify the processing route for your application rather than assuming that every SBA loan follows the same path.
Closing and disbursement
Closing converts an approved transaction into signed loan documents with the required conditions satisfied. Depending on the transaction, outstanding items can involve insurance, liens, property documentation, seller information, or evidence of your contribution.
Disbursement is the release of funds. Confirm whether the lender will release money at closing, pay a seller or vendor directly, or require further documentation before a later release.
Which SBA loan route fits your transaction?
The fastest-sounding program is not automatically the right program. Start with your use of funds, then discuss the available processing route and the remaining work with the lender.
| SBA route | Best for | Practical advantage | Limitation to discuss |
|---|---|---|---|
| Standard 7(a) | Eligible business purposes requiring a flexible financing structure | Supports a broad range of eligible business uses | Lender review and transaction requirements still determine the overall schedule |
| SBA Express | Eligible borrowers considering the Express processing route | Provides a distinct SBA processing framework | The Express label does not promise immediate funding |
| 504 | Eligible major fixed-asset projects | Is structured around qualifying fixed-asset financing | Project documentation and coordination among participating parties affect closing |
Standard 7(a): confirm the lender’s review path
Best for: eligible businesses whose financing needs fit the 7(a) program. Ask whether the lender will use delegated authority and what information it needs before making a credit decision.
The program’s flexibility does not make every transaction simple. An acquisition with unresolved seller documents presents different work from a request supported by complete, consistent operating records.
SBA Express: distinguish response time from funding time
Best for: eligible borrowers whose needs fit the SBA Express framework. The useful question is not whether the program sounds faster; it is which part of your application receives different processing.
An SBA response does not replace lender underwriting or closing. For a 2026 application, ask the lender to explain its current process and provide a separate estimate for disbursement.
SBA 504: plan around the project
Best for: eligible businesses financing qualifying major fixed assets. The financing structure involves a Certified Development Company and a participating third-party lender, so coordination matters.
Ask who owns the project schedule and which documents each participant requires. A review milestone does not resolve an unfinished property, title, or project requirement.
Why SBA loan approval time varies
The schedule changes when the work changes. These factors directly affect what the lender must review or complete:
- Application completeness. Missing records prevent the lender from evaluating the same information you think it already has.
- Financial consistency. Differences among tax returns, financial statements, and debt records require explanations or corrections.
- Processing authority. Delegated and nondelegated routes involve different review responsibilities.
- Transaction complexity. A business purchase or property transaction adds documents and parties beyond your operating business.
- Closing conditions. Insurance, liens, required contributions, and transaction documents must meet the applicable requirements.
- Third-party dependencies. Sellers, appraisers, title providers, and other participants control work outside your immediate reach.
Ask which dependency controls your next milestone. “The application is processing” describes activity, but it does not tell you what must happen next or who needs to act.
How can you keep your application moving?
You cannot guarantee an approval date. You can make the application easier to evaluate and prevent unanswered questions from sitting unresolved.
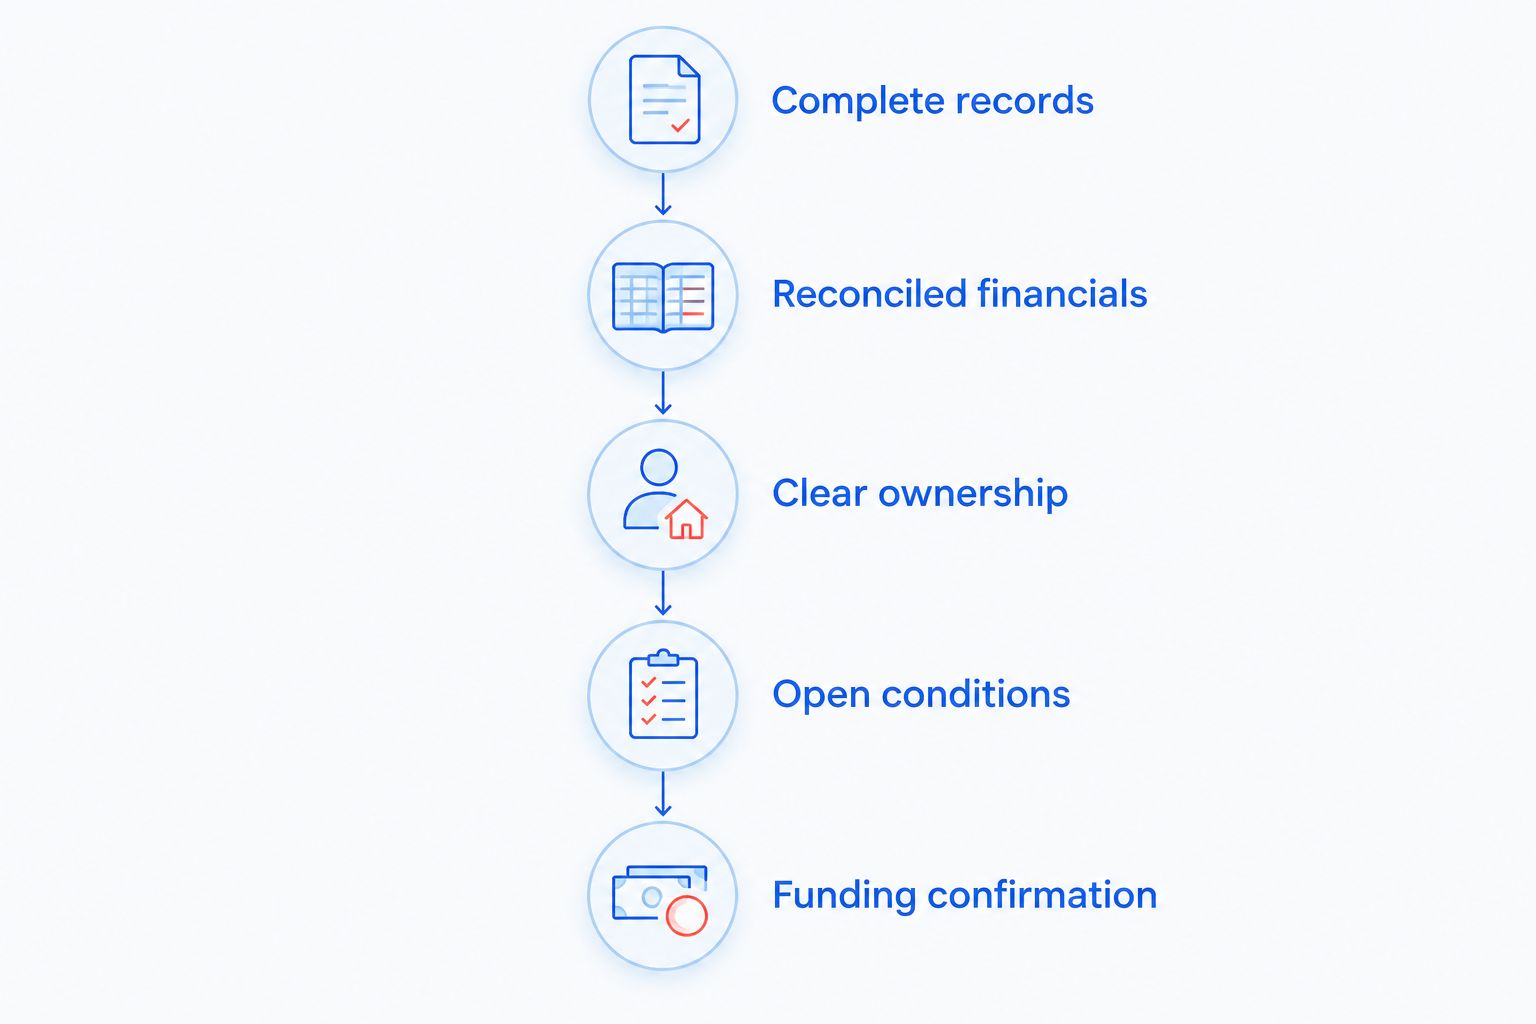
Complete records
Get the lender’s checklist before uploading documents. Use clear filenames, include every requested page, and make sure the records cover the requested periods.
Do not substitute a document because it looks similar. Ask whether the lender accepts the alternative before treating the requirement as complete.
Reconciled financials
Check that your financial statements, debt information, and application tell the same story. Explain material differences rather than expecting the lender to infer the reason.
If your business has seasonal revenue or an unusual expense, provide a factual explanation supported by the relevant records. Projections should connect to identifiable assumptions, not just a growth target.
Clear ownership
Provide consistent ownership and legal-entity information across the application and supporting documents. Tell the lender about a proposed ownership change connected to the transaction.
Ask which owners must supply information or sign documents. Identifying those people early prevents signature requests from becoming a closing surprise.
Open conditions
Maintain a list of unresolved questions and conditions. For each item, record the responsible person, the requested document or action, and the next follow-up date.
Separate items needed for a credit decision from items needed for closing. That distinction makes a status update useful instead of merely reassuring.
Funding confirmation
Before committing to a seller or vendor deadline, ask the lender what must happen before disbursement. Confirm where the money goes and whether your transaction requires anything after signing.
Keep that confirmation with your closing records. A planned release date is more useful when everyone understands the remaining conditions.
What should you ask before accepting a timeline?
Use these 6 questions to turn a broad estimate into a working schedule. Request answers that identify a milestone, an owner, and any remaining condition.
- When does your estimate start? Establish whether the clock begins at initial submission or after the lender accepts a complete file.
- What does approval mean here? Identify whether the estimate describes a lender decision, SBA processing, or readiness to close.
- Which processing route applies? Confirm how the lender will handle the SBA portion of the application.
- What remains unresolved? Request the actual outstanding-item list rather than a general status description.
- Who controls the next step? Identify whether action belongs to you, the lender, the seller, or another participant.
- What must happen before disbursement? Get a separate explanation of closing conditions and fund-release requirements.
Track 3 dates in your 2026 funding plan: your business deadline, the lender’s estimated decision date, and the estimated disbursement date. They serve different purposes. If they do not align, address the gap before making a commitment.
Does SBA approval mean the money is ready?
No. SBA approval does not mean the money is ready for use. Your lender still needs to complete the applicable closing and disbursement requirements.
Ask for the remaining conditions in writing. Then confirm whether any condition depends on a third party or on a document you have not yet supplied.
Can you speed up an SBA loan application?
You can reduce avoidable document delays, but you cannot promise an approval date. Complete records, consistent answers, and prompt responses help the lender evaluate your request without repeatedly reopening the same questions.
Do not confuse frequent follow-ups with progress. Ask what action will move the file to its next milestone, then complete that action.
Should you choose business funding support before applying?
Trifecta Business Group is best for small and mid-sized companies seeking business funding alongside marketing and strategic consulting. That service mix fits owners who want to connect a funding decision with a broader growth plan.
Trifecta Business Group’s funding and consulting services do not establish an SBA lender’s approval schedule. Keep the lender responsible for confirming application status, outstanding conditions, and expected disbursement.
FAQ
How long does SBA loan approval take in 2026?
SBA loan approval has no single turnaround time in 2026. Your lender’s underwriting process, the SBA processing route, and closing requirements determine the schedule; request an estimate through disbursement.
Does the SBA approve every loan directly?
No. Participating lenders with applicable delegated authority can make specified decisions without a separate SBA credit review for each eligible loan. Ask which processing route applies to your application.
Is SBA Express the same as instant funding?
No. SBA Express is a processing framework, not a promise of instant funding. Lender underwriting, closing conditions, and disbursement requirements still apply.
What does a complete SBA loan application mean?
A complete SBA loan application contains the information the lender requires to review your request. Submitting an online form does not by itself establish that the lender has a complete file.
What happens after my SBA loan is approved?
After approval, your lender completes the applicable closing and disbursement requirements. Ask for the remaining conditions and confirm when the funds will become usable.
Can changing lenders make my SBA loan faster?
Changing lenders does not guarantee a faster SBA loan. A new lender needs to evaluate your request, so compare its remaining requirements with the work already completed before switching.
Can Trifecta Business Group guarantee my SBA approval date?
An SBA approval date depends on the lender’s review and the transaction’s requirements. Trifecta Business Group offers business funding and consulting services; obtain application-specific timing from the lender handling your request.
One last thing
Ask what happens after approval before you apply. That question exposes the gap between a decision milestone and the date your business can actually use the money.
For any 2026 funding decision, build your commitments around disbursement conditions—not an approval label. Keep a written record of the next action and who owns it.
Related guides
- How to apply for an SBA loan
- How to prepare your business for a funding application
- QuickBooks to SBA loan approval: complete workflow
- How to choose the right funding option for business growth
Plan your next funding step
Connect your business funding needs with your growth plan.
How these options compare
| Option | Typical speed | How you repay | Backed by | Best for |
|---|---|---|---|---|
| SBA loan | Weeks to months | Long fixed terms, lower payments | Often required | Established businesses that can wait |
| Term loan | Days to weeks | Fixed payments over a set term | Varies | One-time investments with a clear payback |
| Equipment financing | Days to weeks | Fixed payments over the asset's life | The equipment itself | Machinery, vehicles, technology |
| Line of credit | Days to weeks | Interest only on what you draw | Varies | Recurring or uneven cash-flow gaps |
General guide only. Actual speed, cost and terms depend on the lending partner and your file.
How long does an SBA loan take? +
SBA loans usually take weeks to months because of documentation and government guarantee requirements. Faster alternatives exist if timing matters.
Does applying affect my credit? +
Trifecta Business Group requires no hard credit pull, which does not affect your score. Any hard pull is explained before it happens.
How do I know which funding option fits? +
Start with what the money needs to do, how fast you need it and how you want to repay. Our comparison tool and advisors can help match the program.
Planning your timing
See this month's commercial rate benchmarks before you borrow
Our Small Business Capital & Formation Index tracks the Prime Rate, SBA rate caps, realistic cost ranges by funding type, and new business formation pressure state by state — updated every month.
What are you trying to fund?
Compare flexible working-capital options
Start with working capital and a line of credit, then compare payment structure and speed.
Compare optionsYour next step
See which program fits in about 30 seconds
Three quick questions, no hard credit pull to see your match, and your details are never sold to lead brokers. Commercial financing only — approval is never guaranteed.
Free Trifecta tools
Put this article to work for your business
Keep learning with Trifecta Business Group