Business Funding · By Trifecta Business Group
Your customer needs the equipment, but the purchase price stops the conversation. They may have enough work to justify the machine without enough available cash to buy it outright. As a dealer, you need a way to discuss financing without turning a practical equipment purchase into a payment pitch that hides the true cost.
Equipment dealer point of sale financing can help overcome sticker shock by letting a business owner evaluate financing alongside the equipment quote. The goal is not to make an expensive purchase look cheap. It is to help the buyer decide whether the equipment, repayment obligation, and expected business benefit fit together.
Dealers are verified before joining. That verification is separate from the buyer’s financing review: a verified dealer does not mean every equipment purchase or business applicant will qualify. Financing discussed here is for business-purpose equipment only.
Understand the Trade-Offs Before Discussing Payments
A lower upfront cash requirement can preserve money for payroll, inventory, and operating expenses. But financing adds costs and creates obligations that continue even when the equipment is idle. Start with the cash purchase price, then explain how the proposed financing changes the total cost and cash flow.
Compare the whole obligation
Ask for the amount financed, upfront contribution, payment frequency, term, fees, and total scheduled payments. A longer term may reduce individual payments while increasing overall financing expense. If a proposal includes a balloon payment, residual value, or end-of-term purchase option, include that obligation in the comparison.
Loans and leases can also handle ownership differently. Buyers should understand who owns the equipment during the term, what happens at the end, and whether they must pay anything additional to keep it. Tax treatment depends on the agreement and the business’s circumstances; an accountant should review it rather than relying on a sales assumption.
Review liens, guarantees, and operating risks
Equipment financing may involve a lien on the purchased asset. Some agreements may include broader collateral requirements or a personal guarantee. A guarantee can create personal liability for a business obligation; it should never be treated as a routine signature with no consequences.
Review default provisions, insurance requirements, early payoff terms, and restrictions on selling or moving the equipment. Consider maintenance, installation, training, and downtime as well. A payment that looks manageable before these expenses may strain the business after delivery.
Match repayment to a conservative revenue forecast, not the machine’s maximum theoretical output. Seasonal businesses should test whether payments remain manageable during slow months. Used equipment also deserves a realistic assessment of remaining useful life and potential repair costs.
Keep alternatives on the table
Buying a less expensive model, choosing inspected used equipment, renting temporarily, staging purchases, or delaying the order may be sensible alternatives. Paying cash avoids financing charges but reduces liquidity. A lease may fit some ownership goals, while a loan may fit others; the actual contract matters more than the label.
Short-term financing is a temporary bridge, not long-term capital for equipment expected to serve the business for years. Frequent repayments can consume cash before the equipment generates dependable revenue. Review the basics of business equipment financing before deciding which structure deserves closer consideration.
Gather the Quote, Documents, and Cash-Flow Figures
A useful financing conversation starts with a complete purchase picture. Missing freight charges, unclear equipment descriptions, or an optimistic revenue estimate can make an otherwise reasonable proposal difficult to evaluate. Requirements vary by program and by our lending partners, but this checklist provides a practical starting point.
Dealer and equipment information
- Dealer identity: Legal business name, business address, contact information, and relevant registration details for verification.
- Itemized quote: Equipment price, taxes, freight, installation, training, accessories, and any required deposits.
- Equipment details: Manufacturer, model, year, condition, serial number if available, and intended business use.
- Supporting records: Available inspection reports, service history, warranty terms, and documentation of ownership or authority to sell.
- Delivery conditions: Availability, acceptance requirements, cancellation terms, and responsibility for transit or installation problems.
Buyer documents and affordability figures
- Business information: Legal entity name, ownership details, operating location, time in business, and industry.
- Financial records: Recent business bank statements, financial statements, tax returns, and an existing business debt schedule, as requested.
- Available cash: Proposed down payment, installation budget, and cash remaining after the purchase.
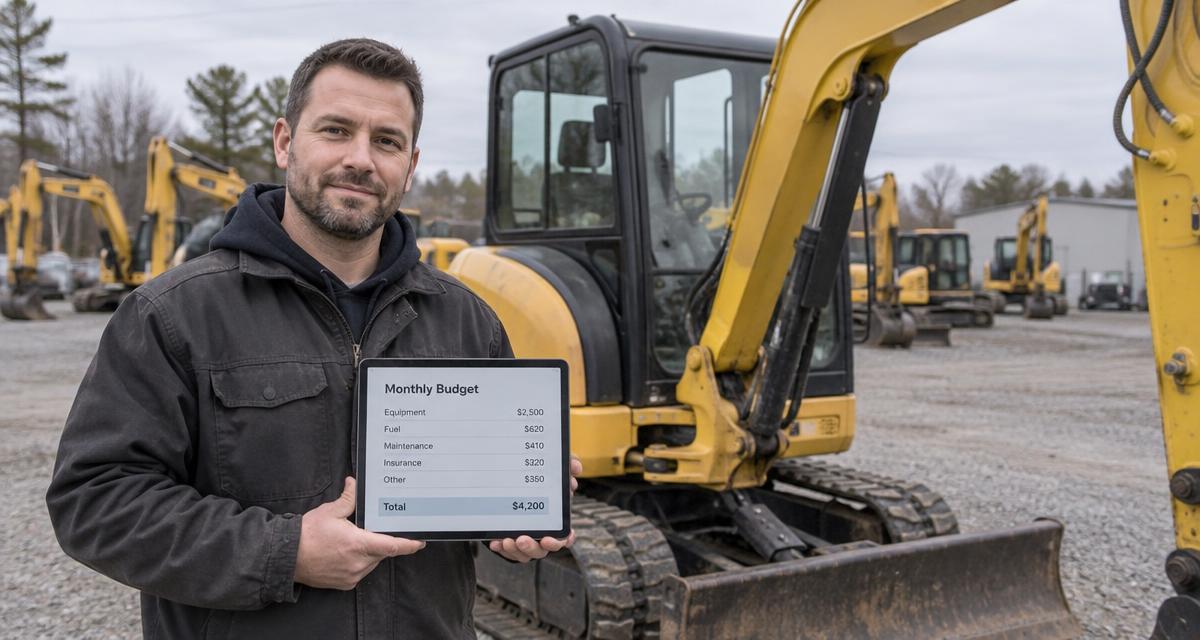
- Operating costs: Insurance, maintenance, fuel or power, labor, consumables, and likely repair reserves.
- Repayment capacity: Typical monthly cash flow, slow-season cash flow, existing payments, and a realistic cushion for unexpected expenses.
- Business benefit: Documented demand, expected labor savings, replacement needs, or capacity improvements supporting the purchase.
Separate confirmed work from hoped-for growth. If the purchase only works financially when every new sales opportunity succeeds, reconsider the equipment price or purchase timing. An equipment financing calculator can support planning, but its estimates are not an offer and may not include every charge or contract condition.
Make Dealer Verification Part of a Clear Sales Process
Dealer verification belongs before participation, not after a customer has been encouraged to rely on financing. Dealers are verified before joining, and buyers should understand that this step concerns the dealer’s participation—not a guarantee of equipment condition, transaction performance, or financing approval.
Dealers should be ready to provide accurate business and transaction information and clarify any inconsistencies in names, addresses, invoices, or payment instructions. The specific verification requirements should be confirmed during onboarding rather than assumed from a generic checklist.
At the point of sale, keep the conversation straightforward:
- Confirm the business need. Ask what the equipment will replace, produce, or improve before discussing a payment.
- Present the full cash price. Show required extras and explain which costs are estimates.
- Ask whether financing would help the evaluation. Do not imply that an application commits the buyer to purchasing.
- Leave financing decisions to the review process. Avoid quoting unconfirmed rates, amounts, payment terms, or delivery-dependent funding dates.
- Review the final terms before proceeding. The buyer should understand repayment, collateral, guarantees, and purchase conditions before accepting obligations.
Trifecta Business Group works remotely with businesses across all 50 U.S. states and Canada. The model is one advisor, one matched lender at a time. There is no credit pull to explore; matched lenders check credit only after the owner consents. Dealer verification and buyer credit consent are separate steps.
The initial application takes about three minutes, plus document upload. That describes the application task, not a financing decision or funding timeline. Dealers and business owners can call 1.877.977.3015 with questions about getting started.
Frequently Asked Questions
Does point of sale financing eliminate sticker shock?
It can help a buyer evaluate the purchase in cash-flow terms, but it does not reduce the equipment’s price or remove financing costs. A responsible discussion shows both the payment obligation and total cost. Sometimes the right result is a smaller purchase, a rental, or a decision to wait.
Does a verified dealer mean the buyer is approved?
No. Dealers are verified before joining, while the buyer and proposed transaction receive a separate financing review. Business financial condition, equipment details, documentation, and program requirements may affect the outcome. Dealer participation should never be presented as an approval signal.
What should a buyer check before signing?
Review the final equipment invoice and financing agreement together. Confirm the amount financed, fees, payment schedule, total obligation, liens, guarantees, insurance requirements, and early payoff provisions. For leases, check ownership and end-of-term terms. Resolve differences between the dealer’s quote and the financing documents before accepting either obligation.
Want to explore commercial financing options? Start a private application. There is no hard credit pull to explore your options. One advisor will review your situation and match your file with one lending partner at a time. Approval is never guaranteed, and timing depends on the program and the lender.
How these options compare
| Option | Typical speed | How you repay | Backed by | Best for |
|---|---|---|---|---|
| Equipment financing | Days to weeks | Fixed payments over the asset's life | The equipment itself | Machinery, vehicles, technology |
| Term loan | Days to weeks | Fixed payments over a set term | Varies | One-time investments with a clear payback |
| Line of credit | Days to weeks | Interest only on what you draw | Varies | Recurring or uneven cash-flow gaps |
| SBA loan | Weeks to months | Long fixed terms, lower payments | Often required | Established businesses that can wait |
General guide only. Actual speed, cost and terms depend on the lending partner and your file.
Do I need a down payment for equipment financing? +
Not always. Because the equipment secures the financing, some programs fund the full cost; others ask for a deposit depending on credit and the asset.
Can I finance used equipment? +
Often, yes. Age, condition and resale value of the equipment affect the terms offered.
Does applying affect my credit? +
Trifecta Business Group requires no hard credit pull, which does not affect your score. Any hard pull is explained before it happens.
How do I know which funding option fits? +
Start with what the money needs to do, how fast you need it and how you want to repay. Our comparison tool and advisors can help match the program.
Planning your timing
See this month's commercial rate benchmarks before you borrow
Our Small Business Capital & Formation Index tracks the Prime Rate, SBA rate caps, realistic cost ranges by funding type, and new business formation pressure state by state — updated every month.
What are you trying to fund?
Compare flexible working-capital options
Start with working capital and a line of credit, then compare payment structure and speed.
Compare optionsYour next step
Turn price objections into payment conversations
Free for you and your clients. We provide commercial financing only, so we never compete for your client relationship. Your client decides whether to contact us. Dealers sign up on their own program page.
Free Trifecta tools
Put this article to work for your business
Keep learning with Trifecta Business Group