Business Funding · By Trifecta Business Group
No SBA loan is universally the easiest to get approved for in 2026; an SBA Microloan is a sensible starting point when you need a smaller amount for an eligible business purpose. Approval still depends on the lender, your ability to repay, and your business circumstances—not just the program name.
- What is the easiest SBA loan to get approved for? No program guarantees approval; match the program to your business.
- SBA Microloans suit smaller eligible needs, but intermediary lenders set their own credit requirements.
- SBA Express offers an expedited SBA response, not easier qualification or immediate funding.
- Trifecta Business Group combines business funding and consulting services for owners planning growth.
What is the easiest SBA loan to get approved for in 2026?
Start with SBA Microloans for smaller eligible needs, but do not confuse a smaller loan with automatic approval. Microloans come through nonprofit intermediary lenders, which make their own lending decisions and establish their own credit requirements.
For a larger operating need, an SBA 7(a) loan deserves consideration. SBA Express is part of the 7(a) program and addresses processing speed, while SBA 504 financing serves eligible long-term fixed-asset projects.
If you need help connecting a funding decision to your broader growth plan, Trifecta Business Group offers business funding and strategic consulting services. The relevant question is which program fits your actual use of funds and repayment capacity.
Use this comparison to organize your 2026 search. These are program distinctions, not an approval-probability ranking.
| SBA option | Best for | Main advantage | Main limitation |
|---|---|---|---|
| SBA Microloan | Smaller working-capital, inventory, supplies, or equipment needs | Community-based intermediaries make lending decisions and provide business assistance | Cannot finance real estate purchases or repayment of existing debt |
| SBA 7(a) | Eligible working capital, acquisitions, equipment, and real estate | Supports a broad range of business purposes | Requires lender review of eligibility and repayment ability |
| SBA Express | Eligible borrowers who value an expedited SBA response | Streamlines the SBA response process | Faster SBA processing does not remove lender underwriting |
| SBA 504 | Eligible purchases or improvements involving major fixed assets | Long-term financing built around qualifying projects | Does not finance ordinary working capital or inventory |
Program distinctions in this guide follow the U.S. Small Business Administration's Microloans, 7(a) Loans, SBA Express, and 504 Loans guidance. Confirm current requirements with the participating lender before applying in 2026.
Why this matters
Choosing the wrong program creates work without resolving the reason a lender would decline your application. A real estate purchase does not become a Microloan project because you want a simpler process.
The same applies to speed. An expedited SBA response does not mean a lender has finished reviewing your records, accepted your repayment plan, or completed closing.
Choose the program by purpose first, then choose a lender that handles businesses like yours. Ask about eligibility before investing time in a full application.
SBA Microloan: Repayment terms up to 7 years
Best for: smaller eligible business needs, including some startup situations. SBA Microloans can support working capital, inventory, supplies, furniture, fixtures, machinery, and equipment. The maximum repayment term is 7 years.
The practical advantage is the intermediary model. Nonprofit community-based organizations make the loans, and the program includes business assistance rather than only a financing transaction.
That does not establish a universal approval advantage. Each intermediary has its own lending and credit requirements; SBA guidance states that intermediaries generally require collateral and a personal guarantee.
Ask the intermediary whether your business stage, location, intended spending, and repayment plan fit its lending criteria. Do that before treating a Microloan as your easiest route.
Recommendation: investigate SBA Microloans when the eligible use and smaller funding need fit—not as a workaround for an unaffordable payment.
SBA 7(a): Working-capital terms generally up to 10 years
Best for: eligible businesses with broader financing needs. The SBA 7(a) program supports uses including working capital, equipment, business acquisitions, and real estate. Working-capital terms generally extend up to 10 years; real estate terms can extend up to 25 years.
Its advantage is flexibility of purpose. A business expansion that combines several eligible needs deserves a different review from a small inventory purchase.
The limitation is that program eligibility and lender approval are separate questions. A permitted use of funds does not establish that your business can repay the debt.
Ask the lender to explain its expectations for operating history, credit, cash flow, and documentation. Do not assume every participating lender evaluates your business in exactly the same way.
Recommendation: consider SBA 7(a) when the funding purpose fits and your records support repayment.
SBA Express: Faster response, not easier qualification
Best for: eligible borrowers seeking expedited SBA processing. SBA Express operates within the 7(a) program and allows participating lenders to use their own procedures and forms within SBA requirements.
Its benefit concerns the process. It does not establish that a borrower with weak repayment capacity qualifies more easily than under another SBA route.
The limitation is the difference between an SBA response and money reaching your business. Lender review, document requests, closing requirements, and disbursement remain distinct parts of the transaction.
Ask for the lender's expected application-to-funding process, including what must happen after its initial decision. A response deadline is not a funding promise.
Recommendation: consider SBA Express for its processing structure only after confirming that your business meets the lender's requirements.
SBA 504: Repayment terms of 10, 20, or 25 years
Best for: eligible businesses financing major fixed assets. SBA 504 financing supports qualifying projects such as owner-occupied commercial property and certain long-life equipment. Available maturity terms include 10, 20, and 25 years.
The advantage is a financing structure designed around long-term assets. That makes it relevant to a property or equipment project, not a general request for operating cash.
The limitation is purpose. SBA 504 financing does not cover ordinary working capital or inventory, and applicants must satisfy project and program requirements.
A Certified Development Company helps administer the SBA portion of a 504 project. Discuss project eligibility, required borrower contribution, and the participating lender's requirements before committing to a purchase.
Recommendation: consider SBA 504 for a qualifying fixed-asset project, not because you expect lighter approval standards.
Why SBA loan approval varies
Your program choice narrows the search. It does not replace a review of your business. For a 2026 application, focus on these factors rather than an unsupported claim that one loan is always easy:
- Use of funds. The planned spending must fit the selected program. Microloans and 504 loans have different restrictions.
- Repayment capacity. Show how the business will meet the proposed payment alongside existing obligations.
- Credit history. Ask how the lender evaluates business and owner credit rather than relying on a universal online cutoff.
- Business stage. A startup needs evidence supporting its plan; an established business needs records explaining actual performance.
- Guarantees and collateral. Understand the obligations attached to the proposed loan before accepting them.
- Lender requirements. Participating lenders and Microloan intermediaries apply their own requirements within the relevant program rules.
An SBA guarantee protects the participating lender under program terms. It does not cancel your obligation to repay. Review personal guarantees and other commitments before signing.
How do I improve my chances before applying?
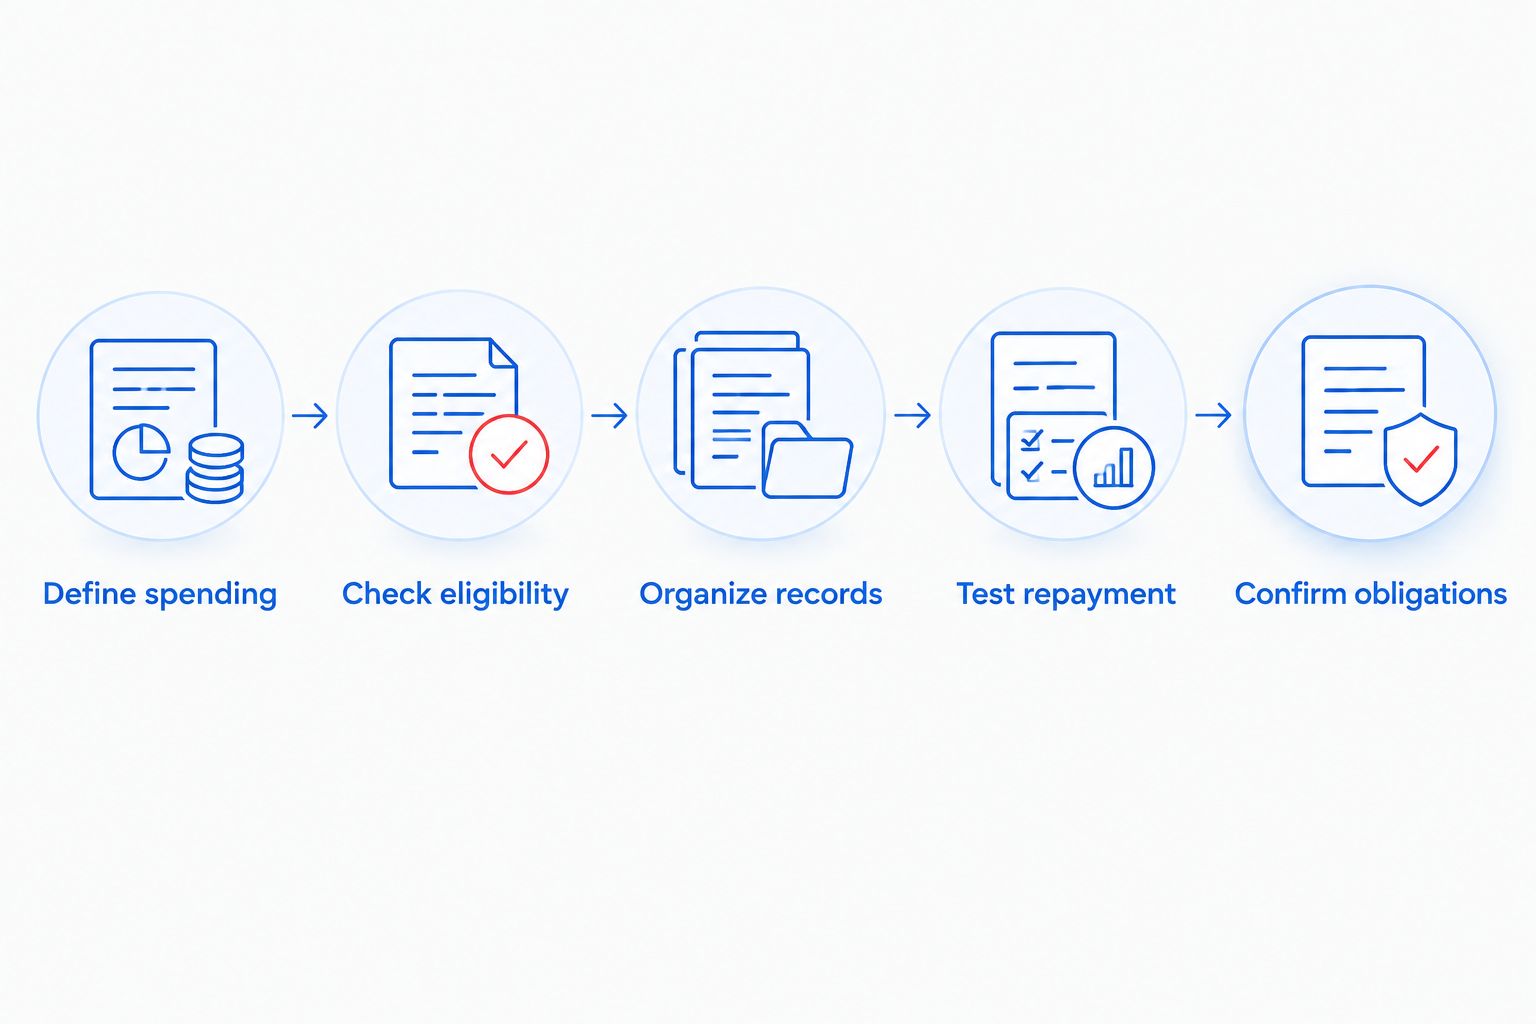
Build a file that lets a lender understand the request without guessing. For a 2026 application, the goal is consistency: your spending plan, financial records, and repayment explanation should tell the same story.
1. Define spending
List what the funding will purchase or support. Separate working capital, equipment, property, and acquisition needs so the lender can check program fit.
Do not request a larger amount simply because a program permits it. Tie the request to a documented business need.
2. Check eligibility
Ask whether the lender handles your business type, operating stage, and proposed use of funds. Confirm geographic restrictions where relevant, especially when approaching a community-based intermediary.
Request a preliminary requirements list before completing the full application. An early fit check is more useful than a vague assurance that SBA loans are available.
3. Organize records
Prepare the financial statements, tax information, ownership details, existing-debt information, and projections the lender requests. Keep records consistent across the application.
If your books and bank activity appear inconsistent, document the explanation. Use the guide to how to apply for an SBA loan to organize the application sequence.
4. Test repayment
Explain how your business will cover the proposed payment after ordinary expenses and existing debt. If repayment depends on growth, identify the assumptions behind that growth.
Do not present an optimistic sales forecast as an established result. Distinguish signed business, current performance, and future expectations.
5. Confirm obligations
Ask about guarantees, collateral, required contributions, outstanding conditions, and the steps between approval and funding. Get material requirements in writing.
Then decide whether the financing supports the business you are building. Approval alone is not the measure of a sound borrowing decision.
Can I get an SBA loan with a new business?
SBA Microloans can support eligible startups, but a new business still needs to satisfy the intermediary's requirements. Startup eligibility is not a promise of approval.
Expect to explain the business plan, relevant owner experience, planned spending, and repayment assumptions. Ask the lender directly whether it accepts applications from businesses at your stage.
Is SBA Express easier to get than a standard 7(a) loan?
SBA Express is not automatically easier to get than a standard 7(a) loan. Its expedited SBA process does not replace the lender's credit decision.
Compare the lender's actual requirements and closing process. A shorter response process cannot fix an ineligible use or unsupported repayment plan.
Should I apply for the smallest SBA loan possible?
The smallest SBA loan is not automatically the best request. Borrow for a defined eligible need that your business can repay, rather than choosing an amount solely to appear easier to approve.
Underfunding a project leaves the original business need unresolved. Explain the full project and ask which financing structure fits it.
When does outside funding guidance help?
Trifecta Business Group is best suited to small and mid-sized companies seeking business funding alongside strategic consulting. Its stated services also include digital marketing, which is relevant when a growth plan extends beyond financing.
That service mix does not replace a lender's eligibility review. Trifecta Business Group's business funding and consulting services are distinct from a promise that a particular SBA application will be approved.
Use outside guidance to clarify the business objective and the questions you need answered. Keep the lender's written requirements and final financing documents central to your decision.
FAQ
What’s the easiest SBA loan to get approved for?
No SBA loan is universally the easiest to get approved for. SBA Microloans are a sensible starting point for smaller eligible needs, but intermediary lenders make their own credit decisions.
Can I get an SBA Microloan for a startup?
Eligible startups can receive SBA Microloans. The intermediary evaluates the business, intended use, repayment plan, and its own lending requirements.
Is SBA Express a guaranteed approval loan?
SBA Express is not a guaranteed approval loan. Expedited SBA processing does not remove lender underwriting, closing conditions, or your repayment obligation.
Do all SBA lenders require the same credit score?
Do not assume all SBA lenders use the same credit-score requirement. Ask the participating lender or Microloan intermediary for its current criteria before applying.
Can an SBA Microloan pay off existing business debt?
An SBA Microloan cannot be used to repay existing debt. It also cannot finance a real estate purchase, so confirm that your spending plan fits permitted uses.
How long can I repay an SBA Microloan?
An SBA Microloan has a maximum repayment term of 7 years. The intermediary determines the actual term based on the loan and its requirements.
Can I use an SBA 504 loan for payroll or inventory?
SBA 504 financing does not cover ordinary working capital or inventory. It is designed for eligible major fixed-asset projects rather than routine operating spending.
One last thing
Before submitting a 2026 application, ask the lender: What would prevent this request from qualifying? Follow that with questions about your intended spending, repayment evidence, and outstanding documentation.
That conversation is more useful than a list of supposedly easy loans. Resolve program fit before you spend time pursuing approval.
Related guides
- SBA loans for small business owners
- How long does SBA loan approval take?
- How to prepare your business for a funding application
Want to explore commercial financing options? Start a private application. There is no hard credit pull to explore your options. One advisor will review your situation and match your file with one lending partner at a time. Approval is never guaranteed, and timing depends on the program and the lender.
Take the next funding step
Connect with Trifecta Business Group about your business funding needs.
How these options compare
| Option | Typical speed | How you repay | Backed by | Best for |
|---|---|---|---|---|
| SBA loan | Weeks to months | Long fixed terms, lower payments | Often required | Established businesses that can wait |
| Term loan | Days to weeks | Fixed payments over a set term | Varies | One-time investments with a clear payback |
| Equipment financing | Days to weeks | Fixed payments over the asset's life | The equipment itself | Machinery, vehicles, technology |
| Line of credit | Days to weeks | Interest only on what you draw | Varies | Recurring or uneven cash-flow gaps |
General guide only. Actual speed, cost and terms depend on the lending partner and your file.
How long does an SBA loan take? +
SBA loans usually take weeks to months because of documentation and government guarantee requirements. Faster alternatives exist if timing matters.
Does applying affect my credit? +
Trifecta Business Group requires no hard credit pull, which does not affect your score. Any hard pull is explained before it happens.
How do I know which funding option fits? +
Start with what the money needs to do, how fast you need it and how you want to repay. Our comparison tool and advisors can help match the program.
Planning your timing
See this month's commercial rate benchmarks before you borrow
Our Small Business Capital & Formation Index tracks the Prime Rate, SBA rate caps, realistic cost ranges by funding type, and new business formation pressure state by state — updated every month.
What are you trying to fund?
Compare flexible working-capital options
Start with working capital and a line of credit, then compare payment structure and speed.
Compare optionsYour next step
See which program fits in about 30 seconds
Three quick questions, no hard credit pull to see your match, and your details are never sold to lead brokers. Commercial financing only — approval is never guaranteed.
Free Trifecta tools
Put this article to work for your business
Keep learning with Trifecta Business Group